Skip to main content

Insights

Access expert research, timely insights, and exclusive webcasts to help you make confident, data-driven decisions.
bca.usp_sr_2026_05_13_cover.png
Report
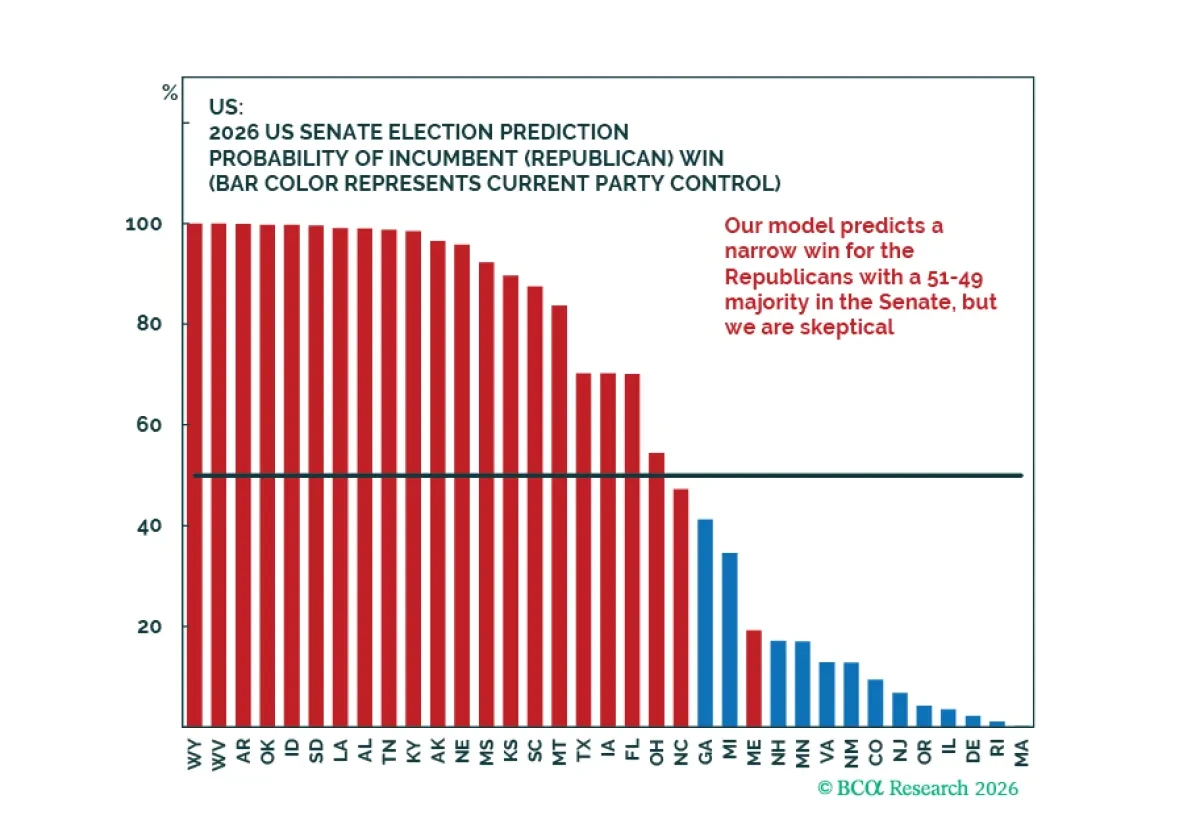
Democrats are likely to win big in this year's midterm elections. Our new quant model still slightly favors Republicans for the Senate, but we expect the oil shock to deliver surprise Democratic victories....
13 May 2026
bca.ets_si_2026_05_12_cms.png
Report
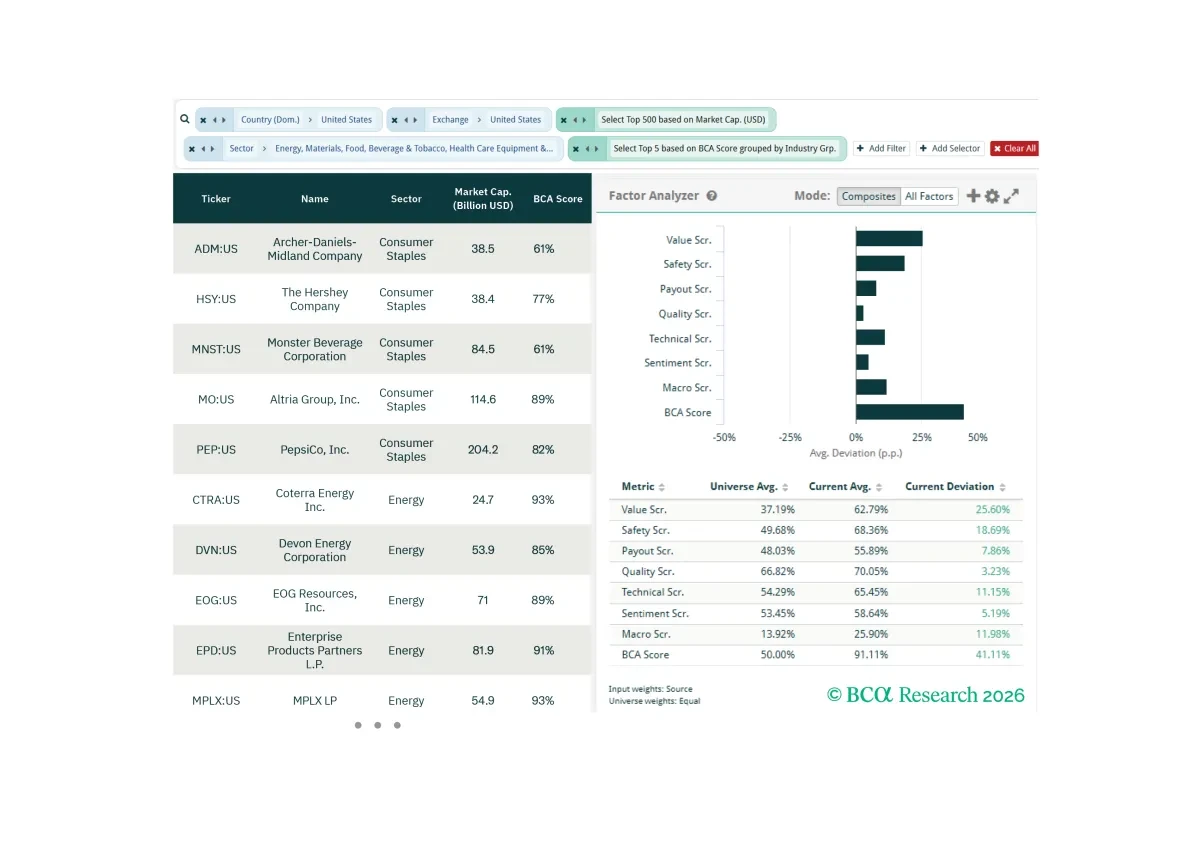
In this screener report, we explore opportunities in Inflation risk, supply-constrained Information Technology stocks, and old-economy cyclicals....
12 May 2026
bca.usbs_si_2026_05_12_cms.png
Report
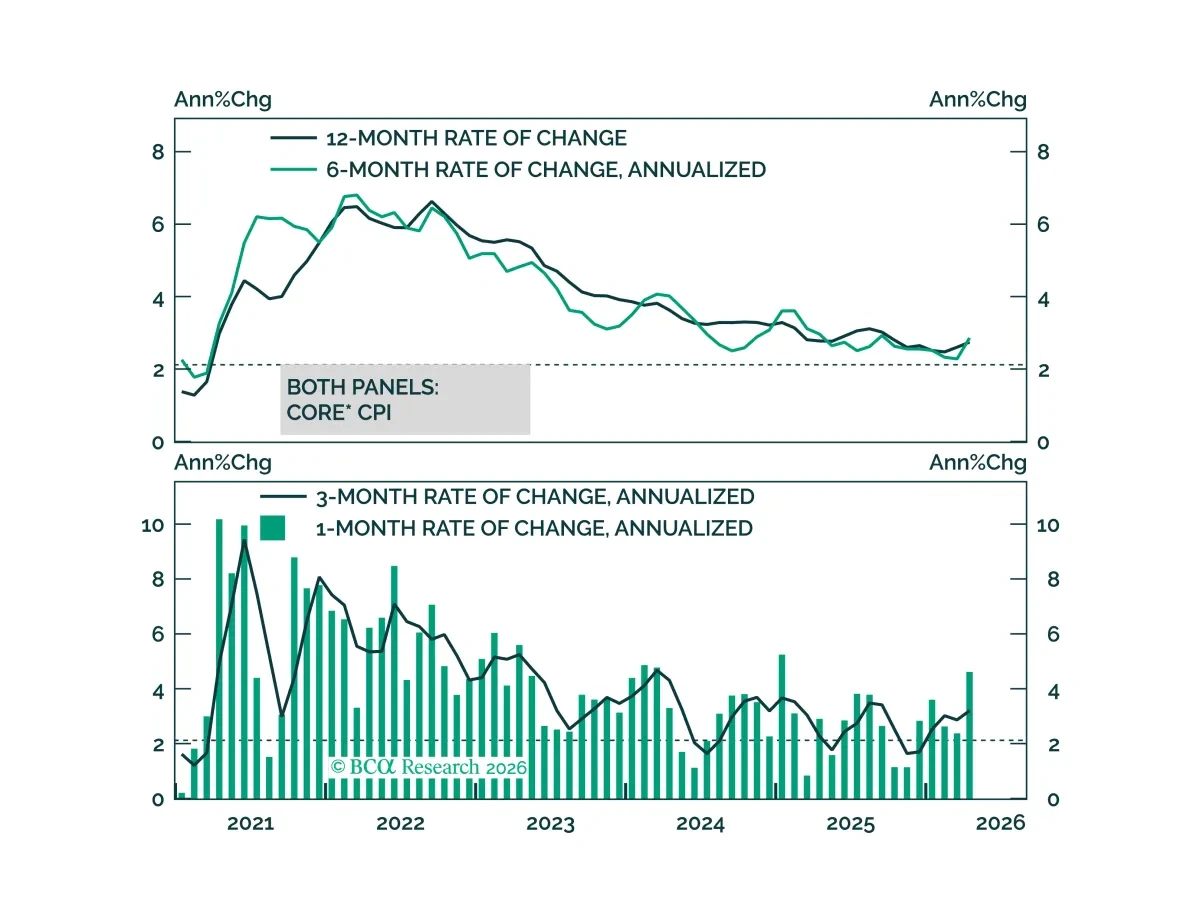
The April CPI report showed clear evidence of the direct effect of higher oil prices on inflation but, so far, limited evidence of passthrough to core....
12 May 2026
bca.pma_sr_2026_05_12_cover.png
Report
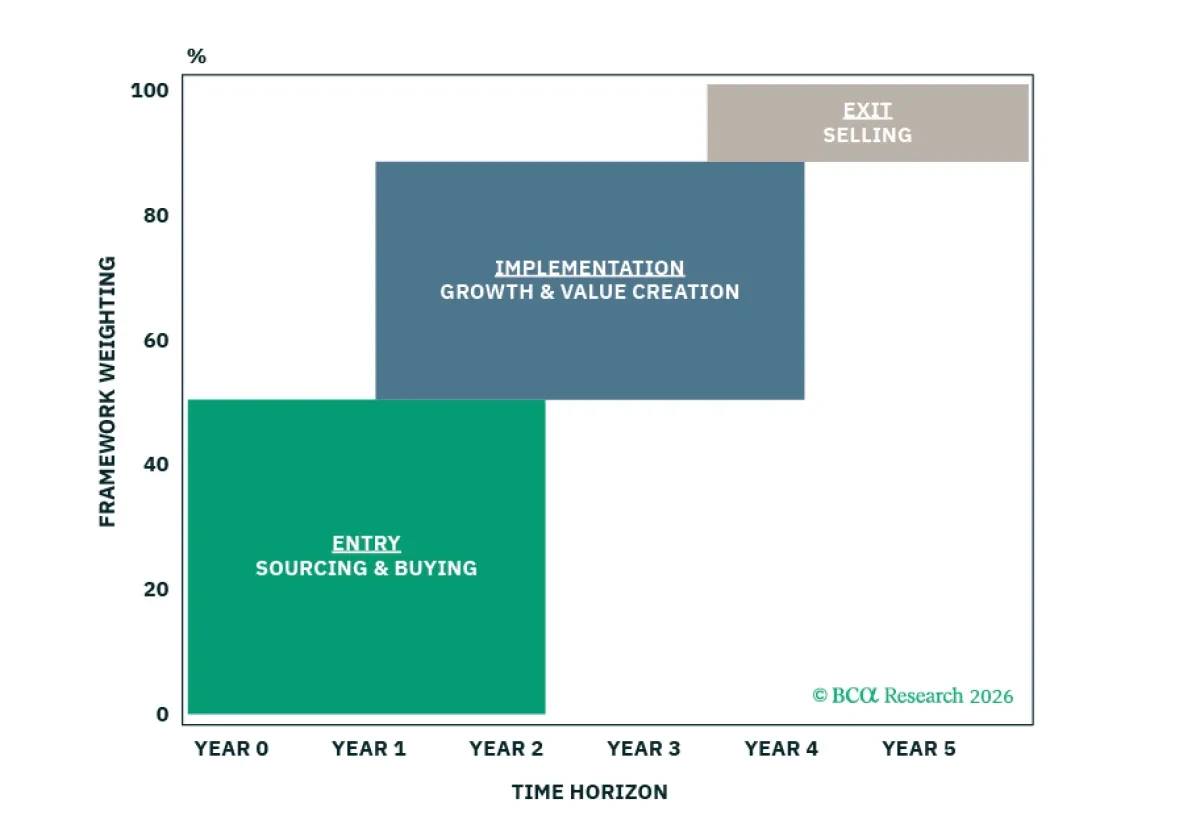
Private Equity fund vehicles may extend beyond 10 years, but the underlying assets that drive performance typically do not. We provide the framework for investors to capitalize on this reality....
gmac_hte_2026_05_12_cms.png
Report
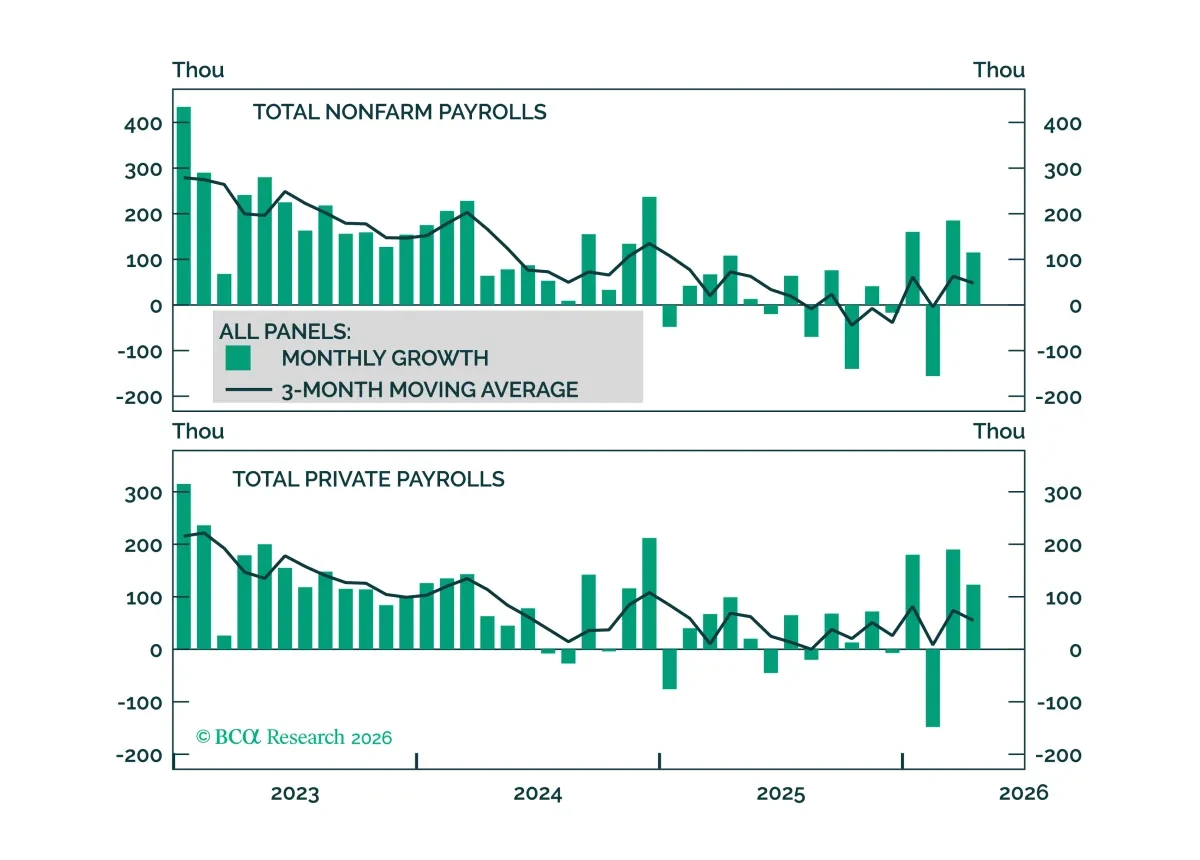
Equities have thrown caution to the wind for much of April and early May. We do not disagree with the sanguine mood, but caution that the Hormuz saga is far from over. Still, the AI capex mania continues and the labor market is firming in the US, suggesting that there is more upside to equities....
12 May 2026
bca.uses_wr_2026_05_11_cms.png
Report
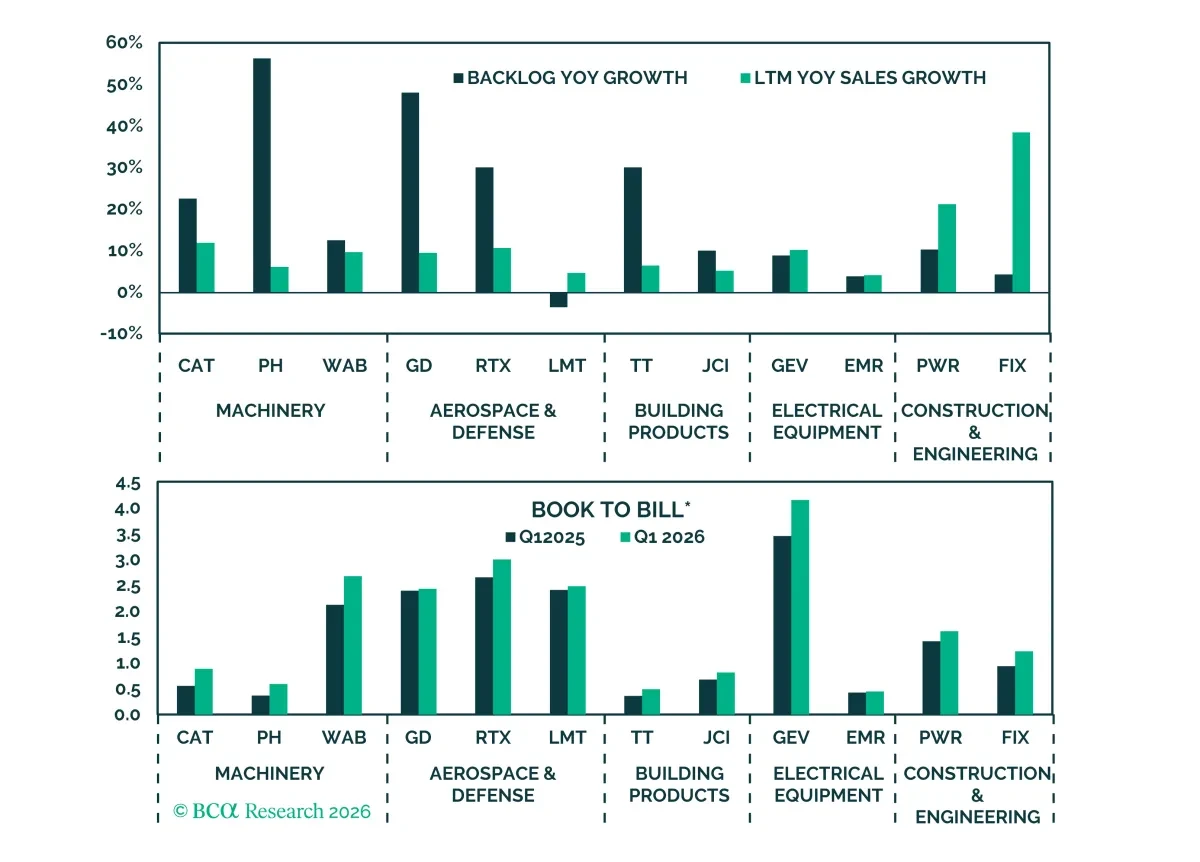
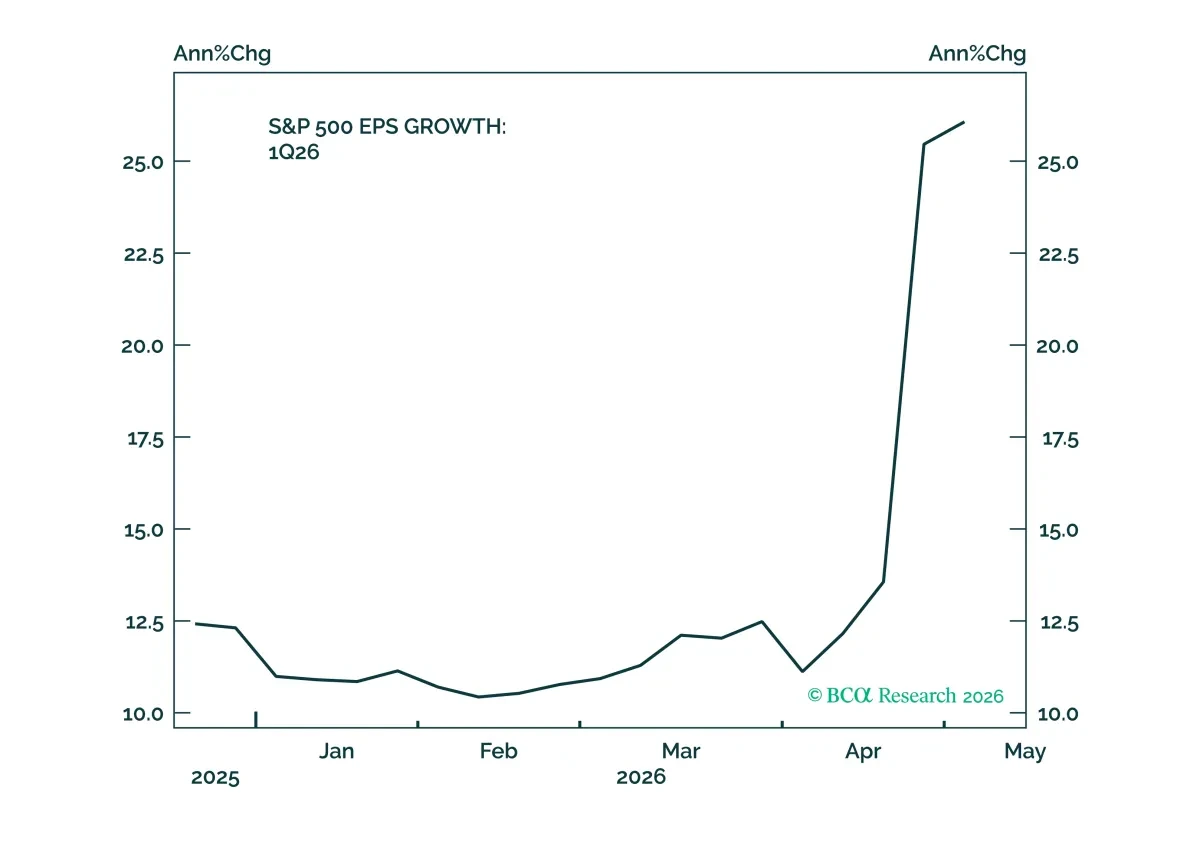
The investment cycle remains firmly intact, driving equity prices and fundamentals, as confirmed by both Q1 data and corporate commentary. Upside surprises, expanding margins, and rising capex expectations point to resilient demand. Companies confirm that AI-related demand is broad and visible, whil...
11 May 2026
bca.usis_wr_2026_05_11_thumbnail.png
Report
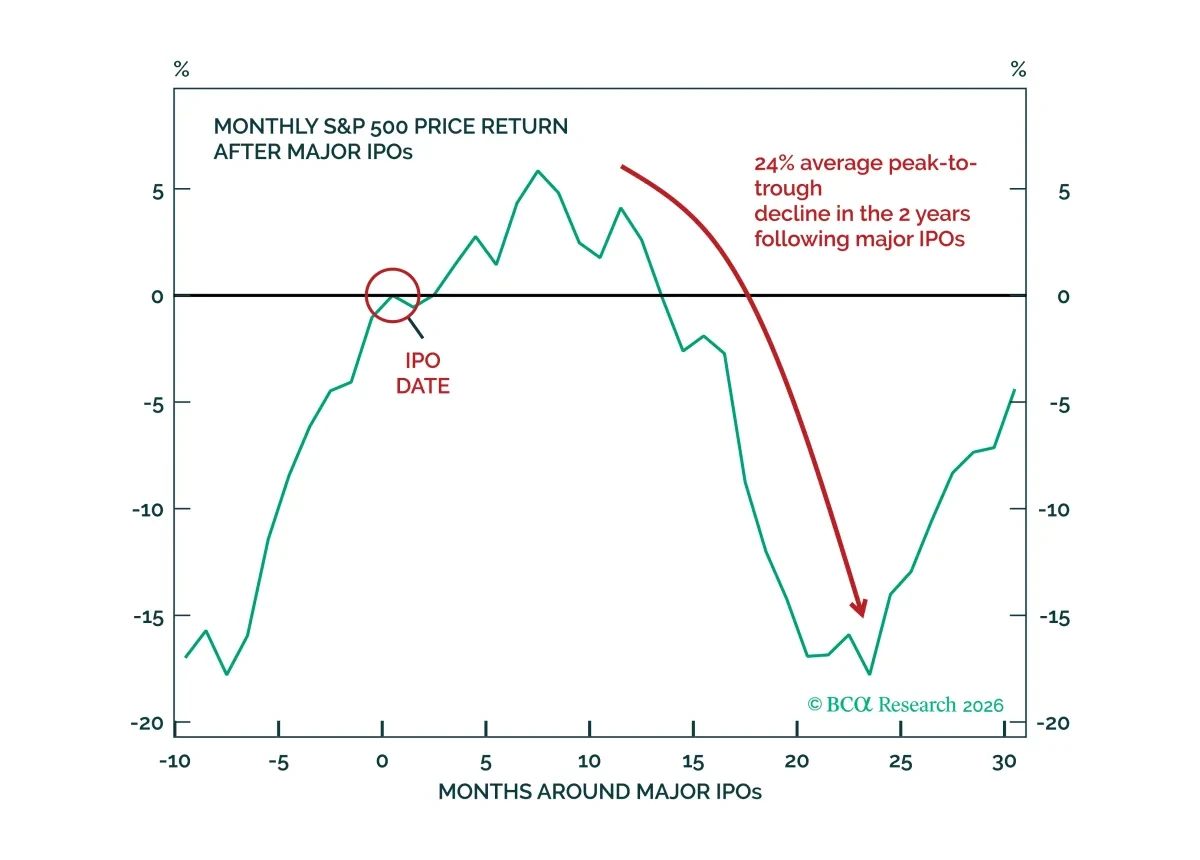
We take stock of earnings, AI capex and the labor market and explain why we think the repeated new highs in the S&P 500 are justified....
11 May 2026
bca.ets_mp_2026_05_08_s1_email.png
Report
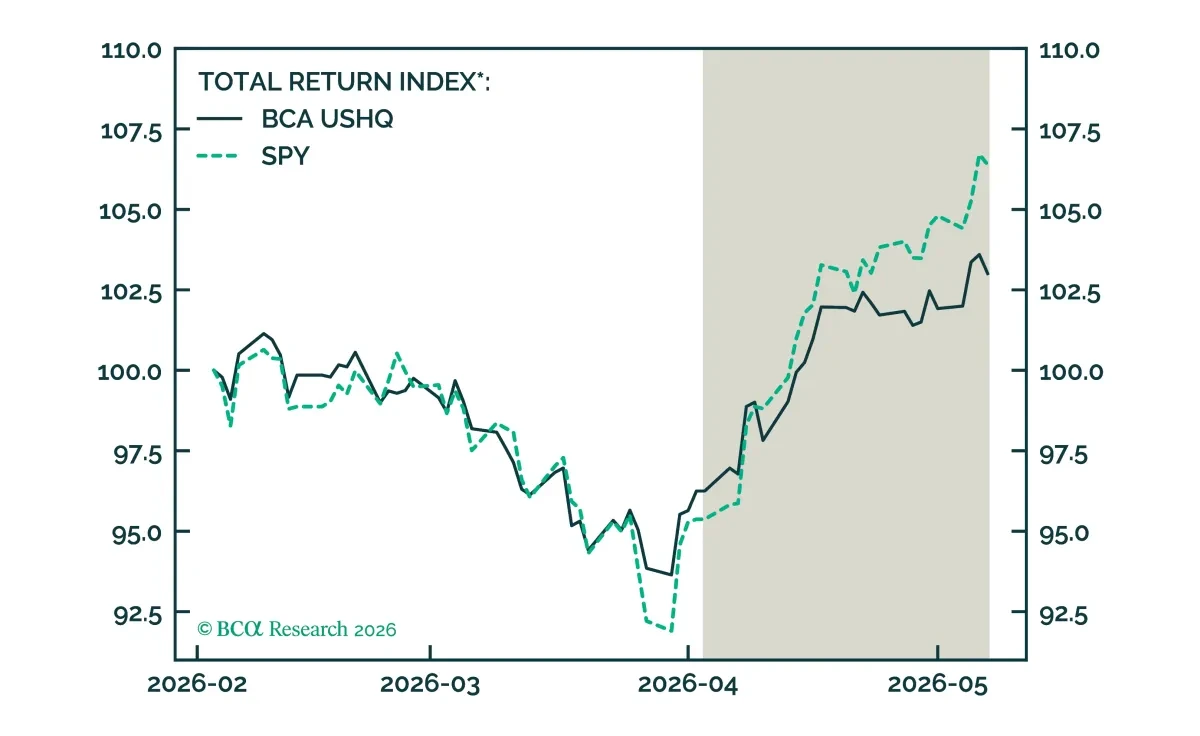
The US High Quality (USHQ) portfolio underperformed its benchmark through April, returning 7.02%, while its SPY benchmark returned 11.55%. On a trailing three-month basis, the USHQ portfolio’s performance was weaker than the benchmark as well, with USHQ underperforming by approx. 338bps....
08 May 2026
bca.usbs_si_2026_05_08_cms.png
Report
Improving job growth keeps Fed rate cuts off the table, but evidence of labor market tightening will be required before rate hikes become part of the discussion....
08 May 2026
Mathieu_Roukaya_Noah.png
Webcast Replay

BCA Chief Strategists, Mathieu Savary, Roukaya Ibrahim, and Noah Weisberger looked at the latest developments in the Strait of Hormuz and the implications for global financial markets.


Topics discussed:

  • The Strait of Hormuz remains closed, and energy markets are tightening again. Is the shock being underpriced?
  • What would a sustained disruption mean for the global growth–inflation trade-off? Is stagflation risk creeping back?
  • Within commodities, where is the real asymmetry now? What’s crowded, and what still offers upside?
  • Can strategic reserve releases truly cap the rally, or do they just delay the adjustment?
  • Equities have remained resilient. Are markets looking through the shock, or misreading it?
  • Where is the tipping point: how much further can oil rise before equities reprice meaningfully?
  • If crude continues higher, which sectors and factors offer the most convex exposure, not just beta?
  • If flows normalize and oil rolls over, where does leadership rotate, and how quickly?