Latest from BCA Research
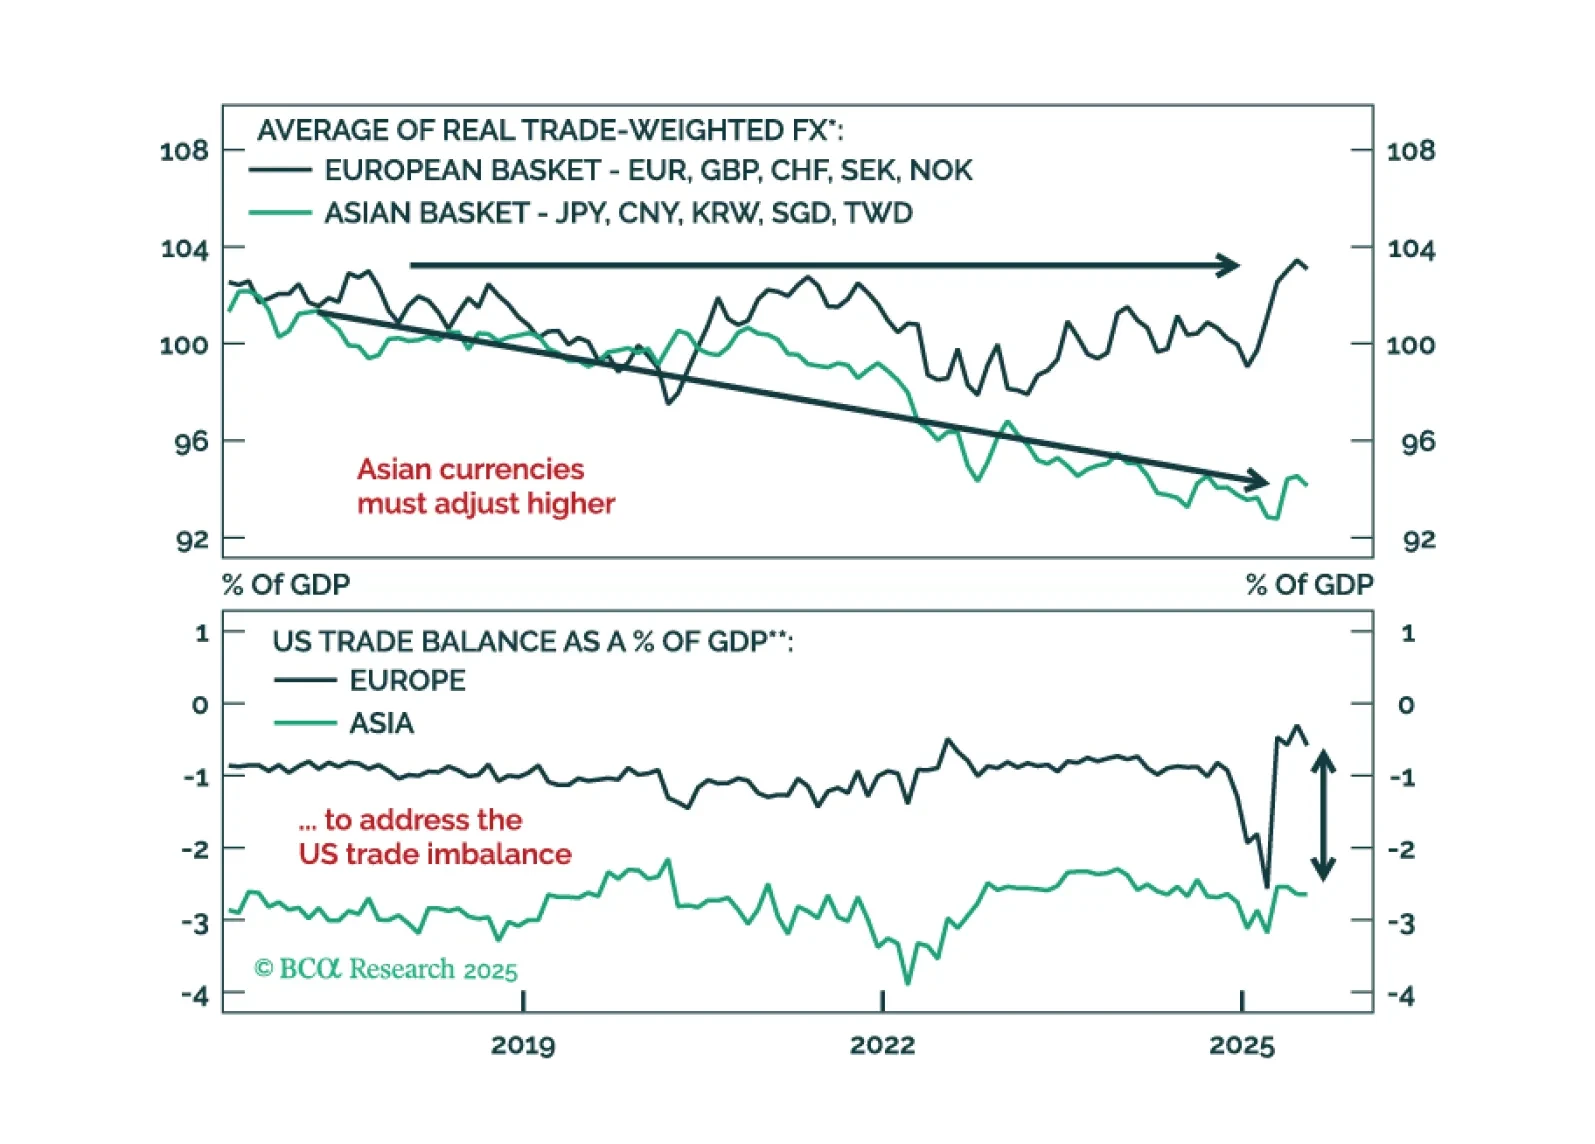
A fleeting greenback rally post Fed rate cut will offer a final chance to reset short dollar exposures. See why undervalued Asian FX are poised to lead the next leg lower in USD and how to position now.

The European Central Bank has achieved a soft landing. Inflation is back to target, with well-anchored inflation expectations. The unemployment rate is historically low, and real economic growth is stable, albeit weak. Given that little to no additional easing will come from the ECB, investors should underweight government bonds relative to equities.
Although our recession conviction has risen, we conclude our strategy review by closing our equity underweight and our fixed income and cash overweights. AI momentum is too strong to have anything more than modest exposure to an equity decline via a small SPY put position.

Several clients have asked the GeoMacro team what we expect the Trump administration to focus on over the next 12 months. These will be critical 12 months as the midterm electoral campaign will be in full swing following Labor Day next year.

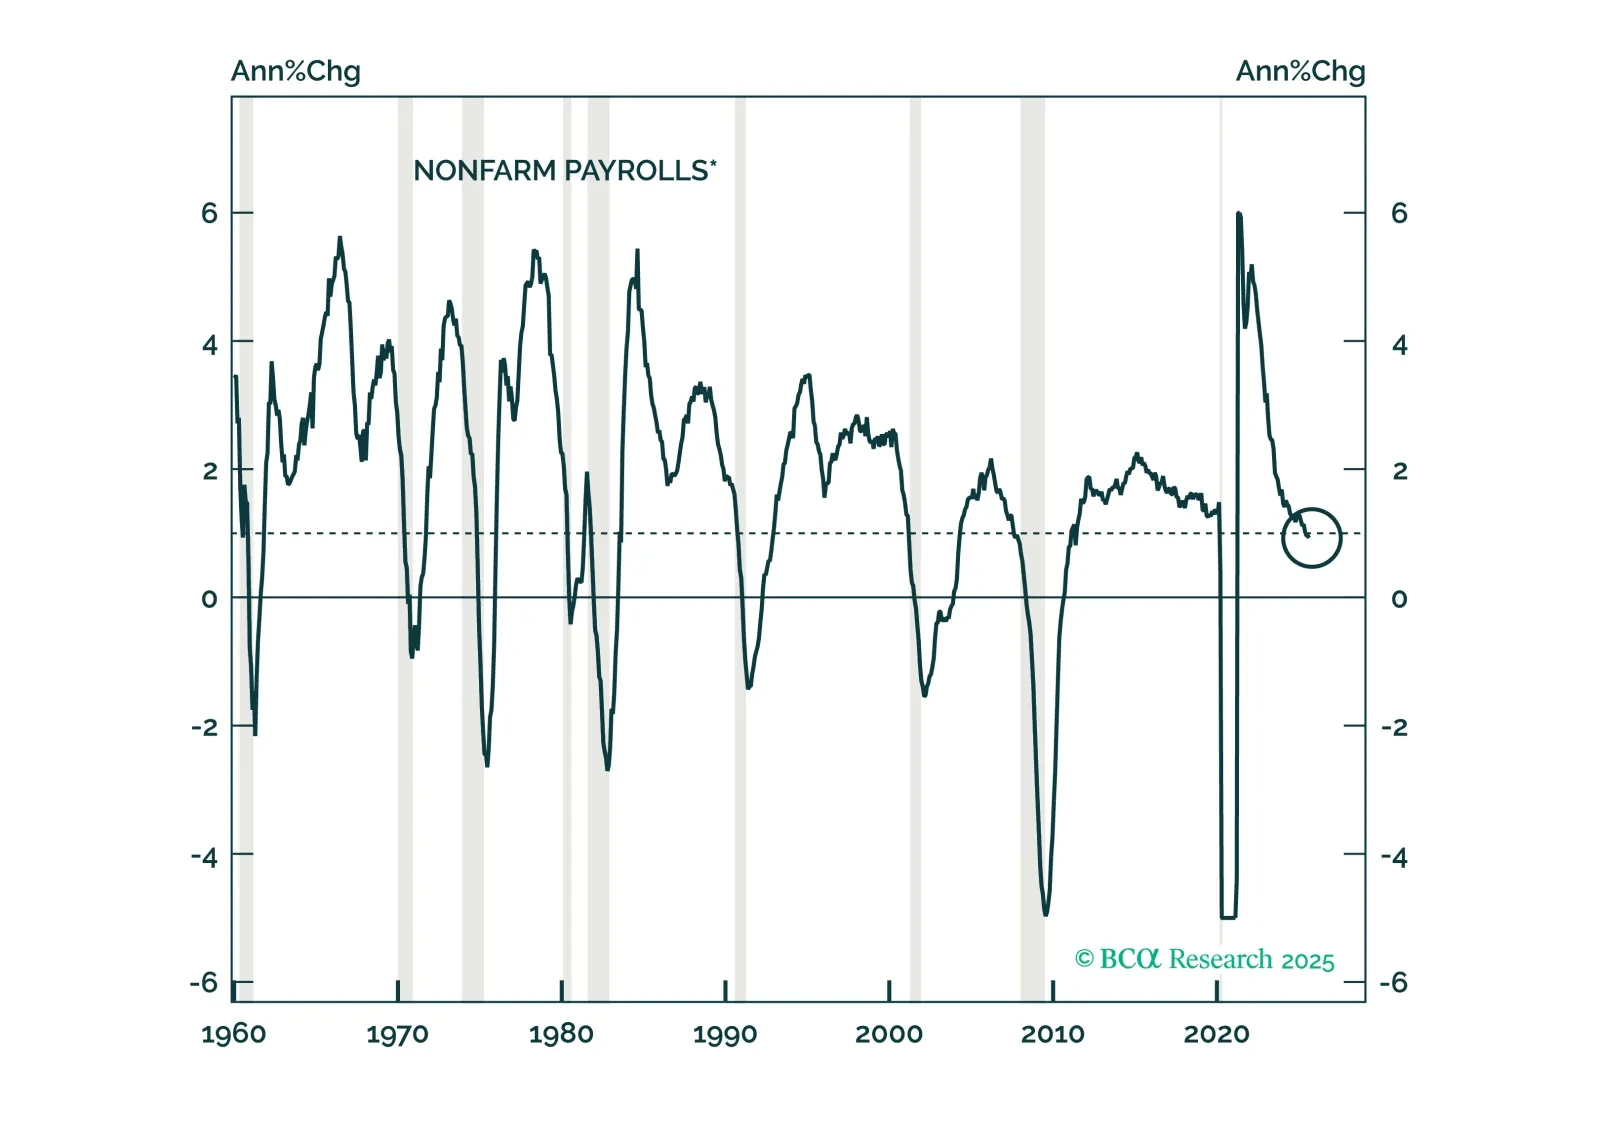
The August employment report showed a modest increase in labor market slack, enough to cement a 25-basis-point rate cut this month.

The US High Quality (USHQ) portfolio outperformed its benchmark through August, returning 5.39%, whilst its SPY benchmark returned 3.75%. On a trailing three-month basis, the USHQ portfolio’s performance was weaker than the benchmark, but the gap narrowed, with USHQ underperforming by approximately 450bps.

Investors will be disappointed if they buy into the China rally and then Russia escalates the war in Ukraine.

Inflation expectations in the US remain reasonably well anchored and there are few signs of a brewing wage-price spiral. Thus, the near-term risks to growth outweigh the risks of higher inflation. Looking beyond the next year or two, however, we are worried about stagflation.


The NFL and NBA grab the headlines, but growth beats size. This report reveals the story behind Major League Soccer (MLS) growth. Valuations have jumped, yet plenty of upside remains—making the MLS relatively attractive compared to other US major leagues.