Latest from BCA Research

The Q2 reporting season underscores the resilience of corporate earnings, supporting our bullish outlook for equities, an outlook further bolstered by expectations of fiscal and monetary easing. However, for now, we are booking profits, closing overweights in Technology and Growth, and initiating a new overweight in Real Estate.

This week our three screeners identify: Broader and more accessible tech-driven equities, US equities exposed to cryptocurrencies, and doubling-down on top-decile stocks.

Economic activity and hiring cooled significantly in the first half of the year. The most important question for investors is whether this signals an imminent increase in labor market slack.
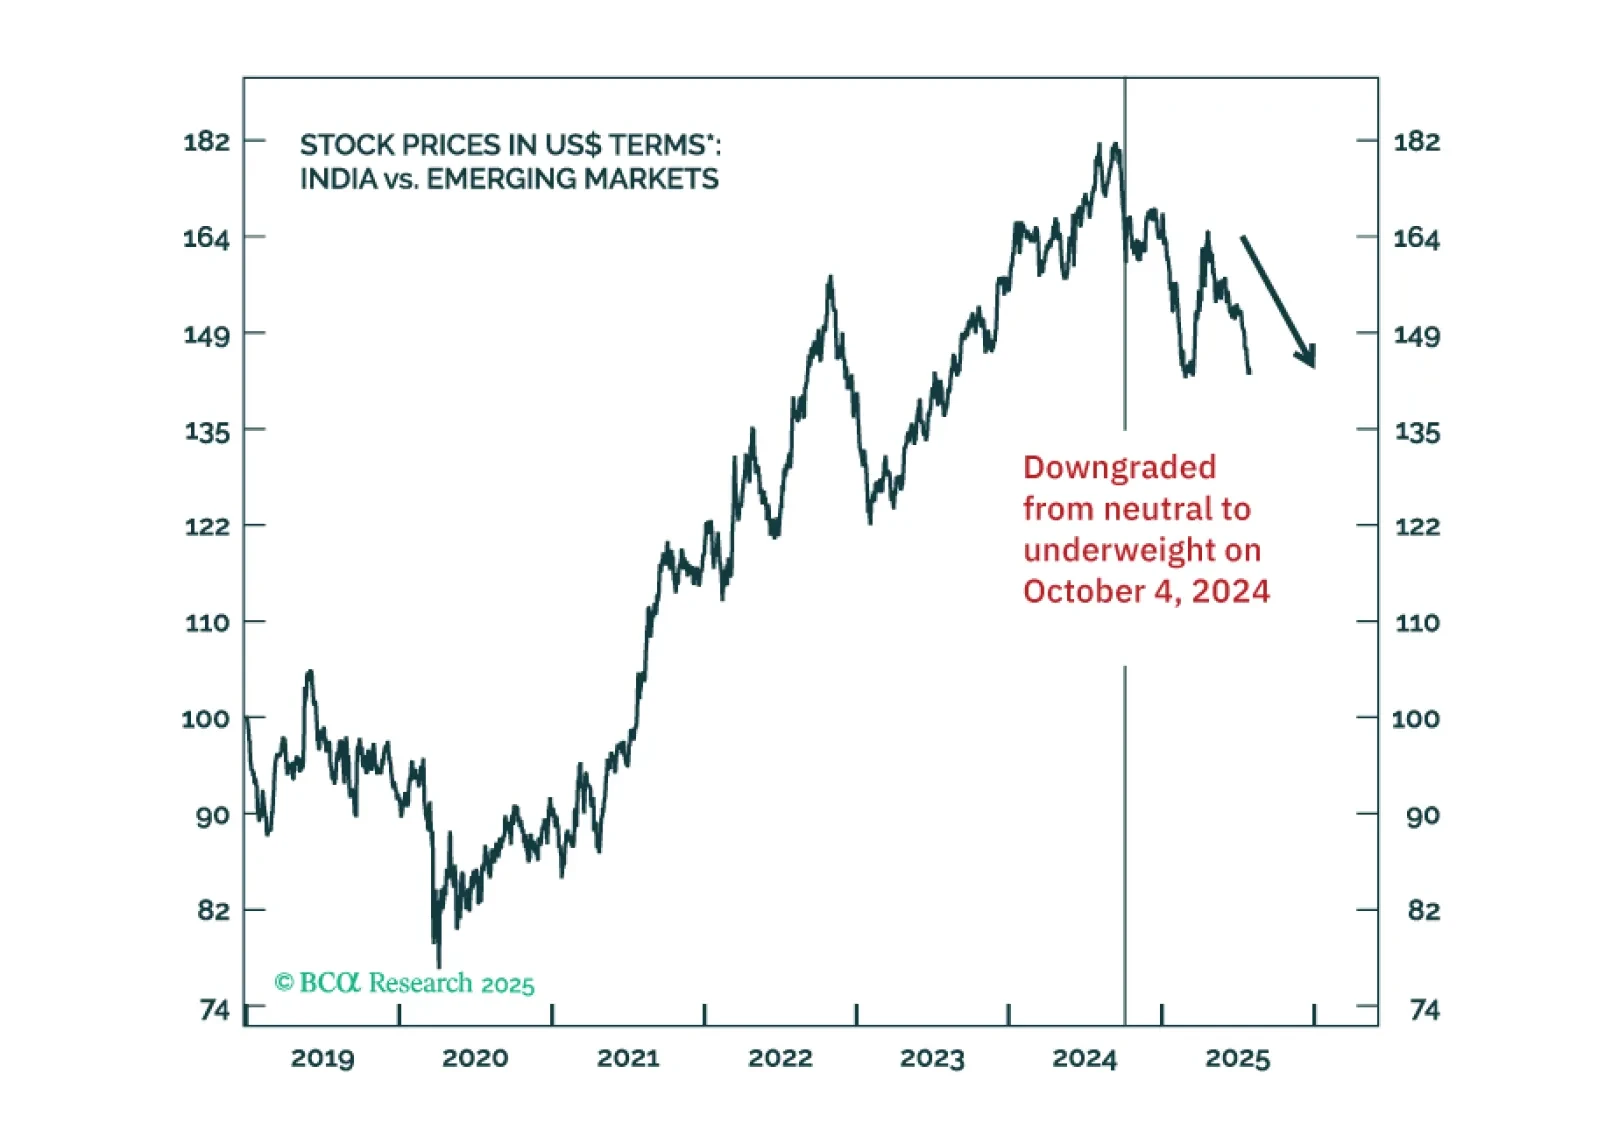
A high US tariff and the lingering uncertainties on the US-India trade deal will hurt investors sentiment. This and contracting corporate profits will push share prices lower. Stay underweight Indian stocks.
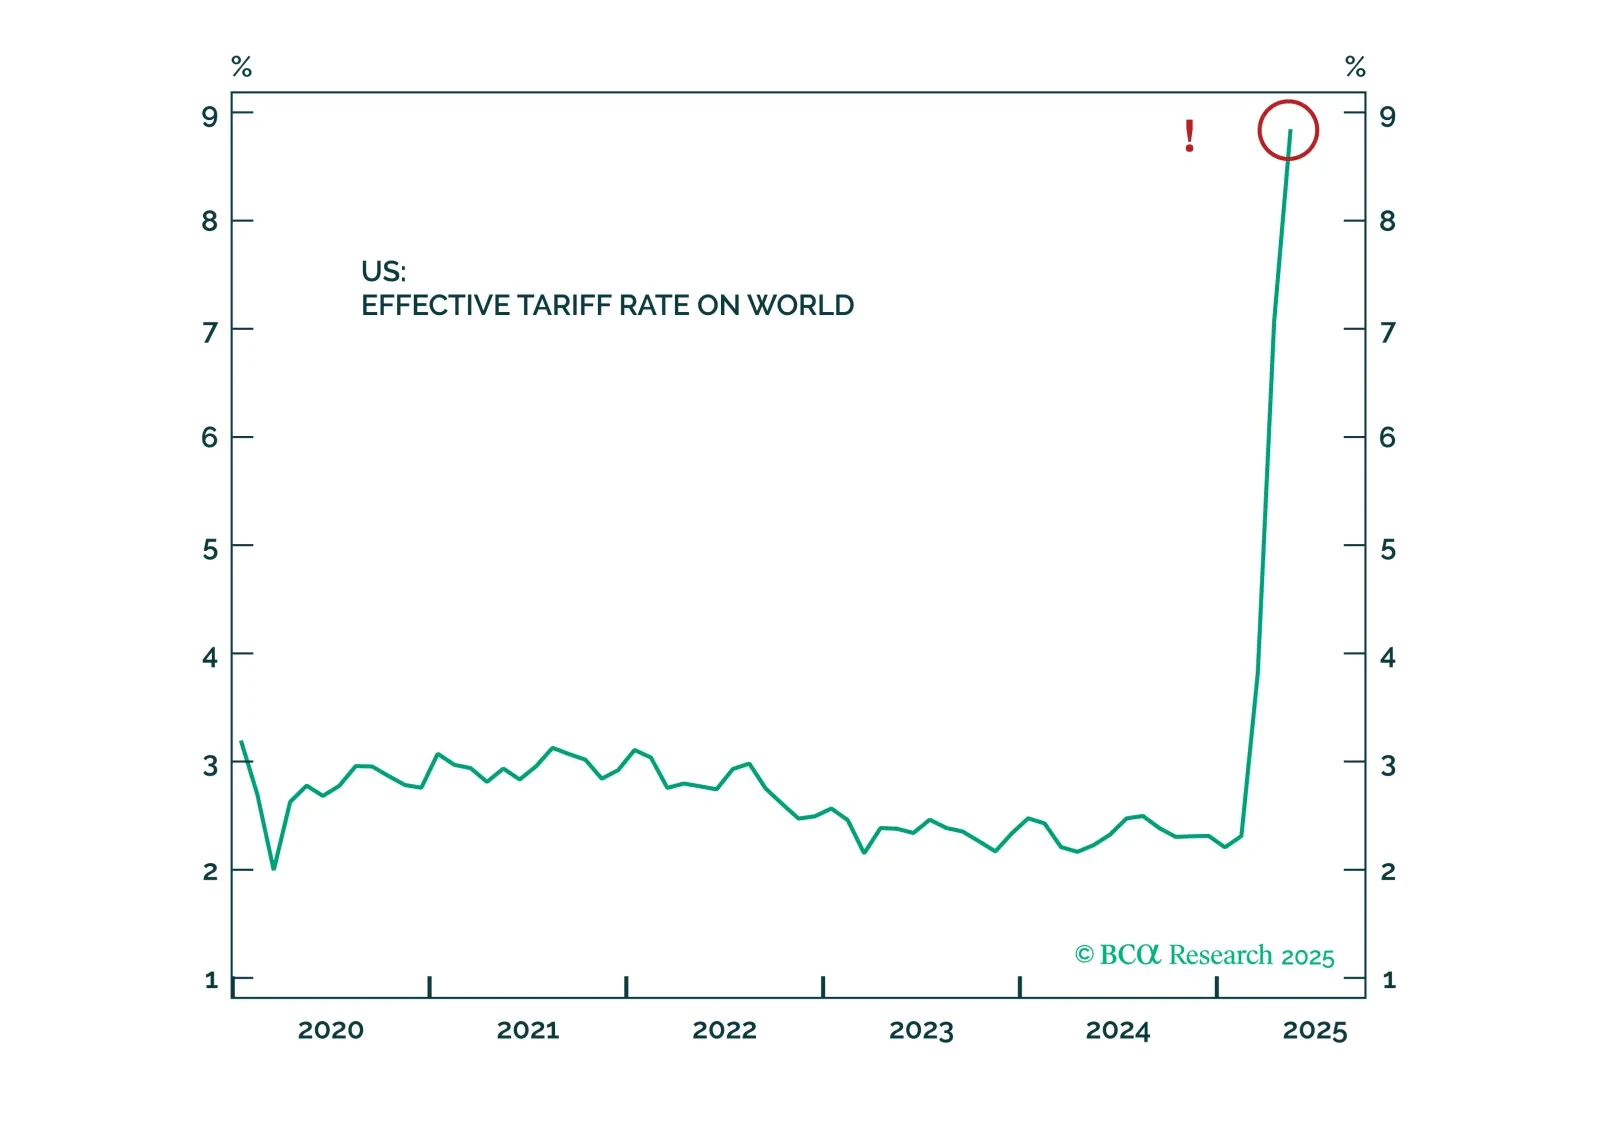
Investors should stick to a defensive stance in the very near term as the Russia-Ukraine conflict and persistent trade tensions cause market volatility.
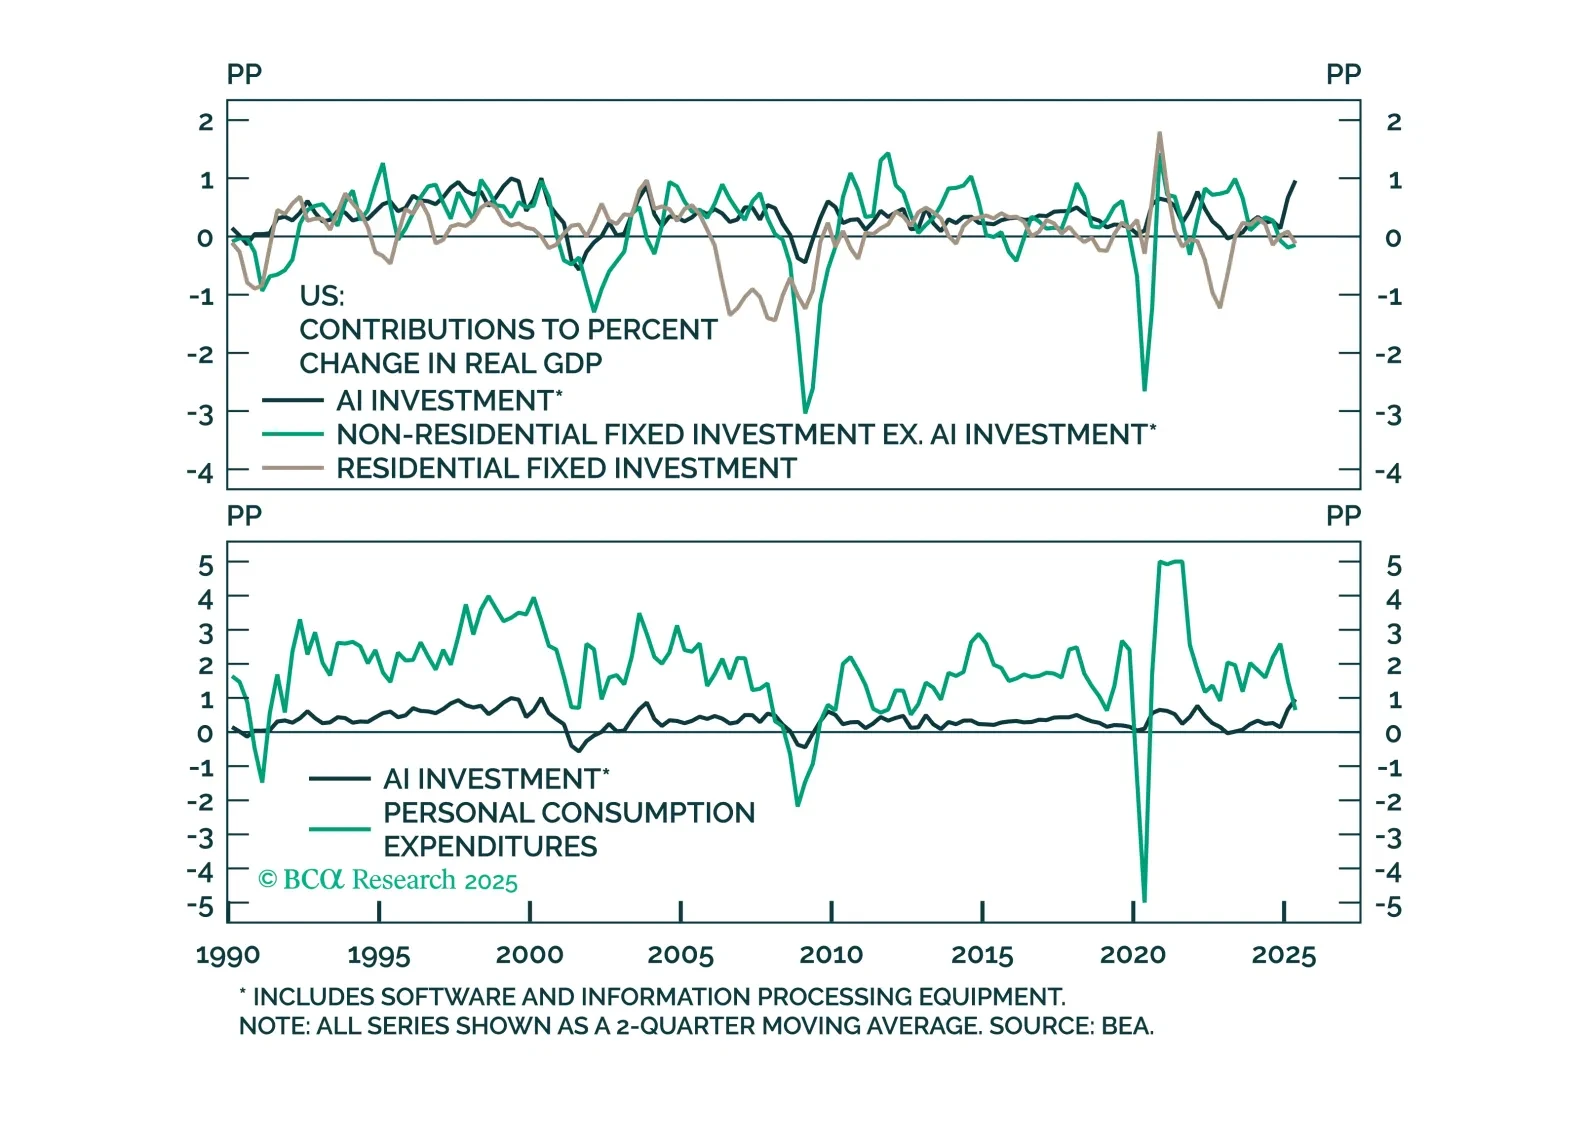
Over the first half of 2025, AI capex outpaced both consumption and all other investments in its contribution to US growth. Like all other capex cycles this one will end in tears. However, the indicators we track suggest that AI capex can continue supporting growth and markets for now. Remain Neutral on equities. Upgrade Health Care to Overweight and downgrade Consumer Staples to Neutral. Buy tail risk protection.


MacroQuant is recommending that equity investors keep their finger near the eject button but avoid pressing it for now. The model is warming up to the dollar again and sees scope for oil prices to rise.

The yen’s discount, surplus, and rising real rates line up for a multi-quarter surge. Find out why EUR/JPY is the first short and when USD/JPY follows.