Skip to main content

Latest from BCA Research

MacroQuant’s US equity z-score is dangerously close to the -1 threshold. Moves below that threshold have reliably coincided with equity bear markets in the past. As such, MacroQuant recommends an underweight on stocks, offset by an overweight on bonds and cash.
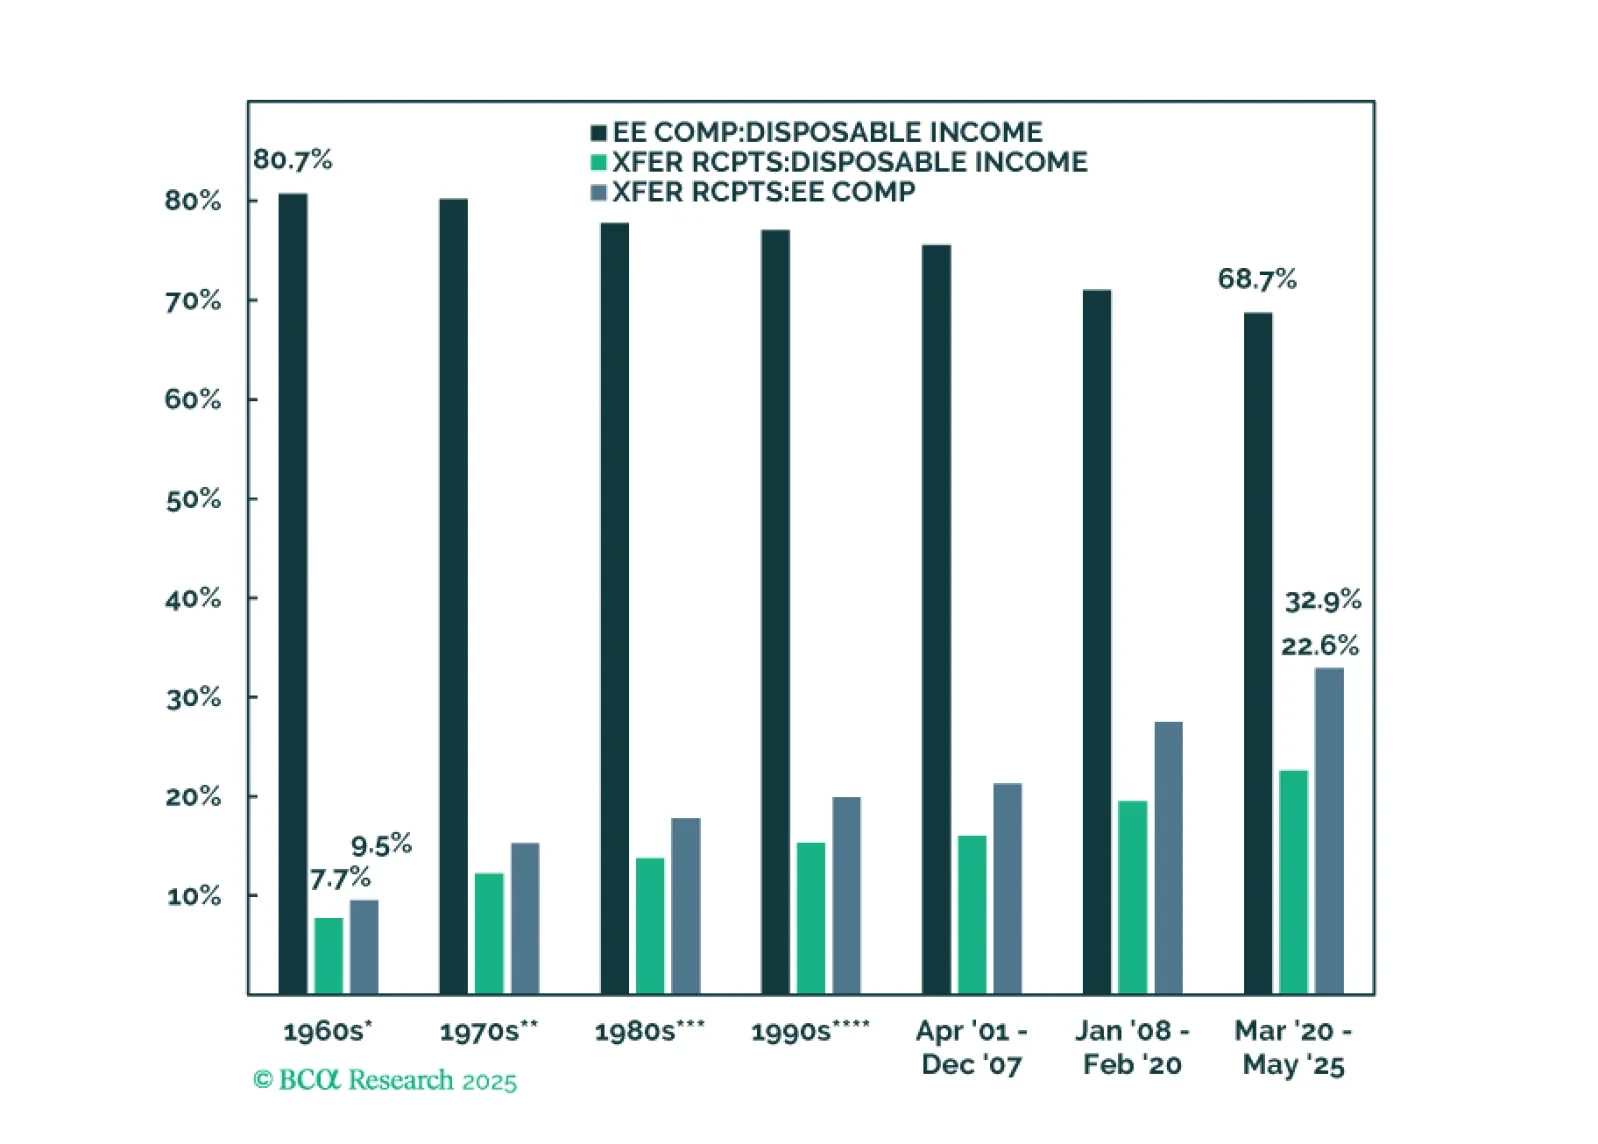
Special Report Our Special Report is a graphical comparison of the consumer’s position in the current cycle to every cycle from 1960 forward. The bad news is that disposable income is increasingly reliant on government transfers and the labor market is softening. The good news is that the balance sheets of households in the lower half of the wealth distribution have improved a lot.
The Life and Health Insurance industry offers downside protection and portfolio diversification in the event of a market correction, surging inflation, or stubbornly high interest rates.
This week our three screeners explore: UK stocks that are cheap and offer a geopolitical hedge; French stocks that are sensitive to China; and US Value and dividend paying stocks.
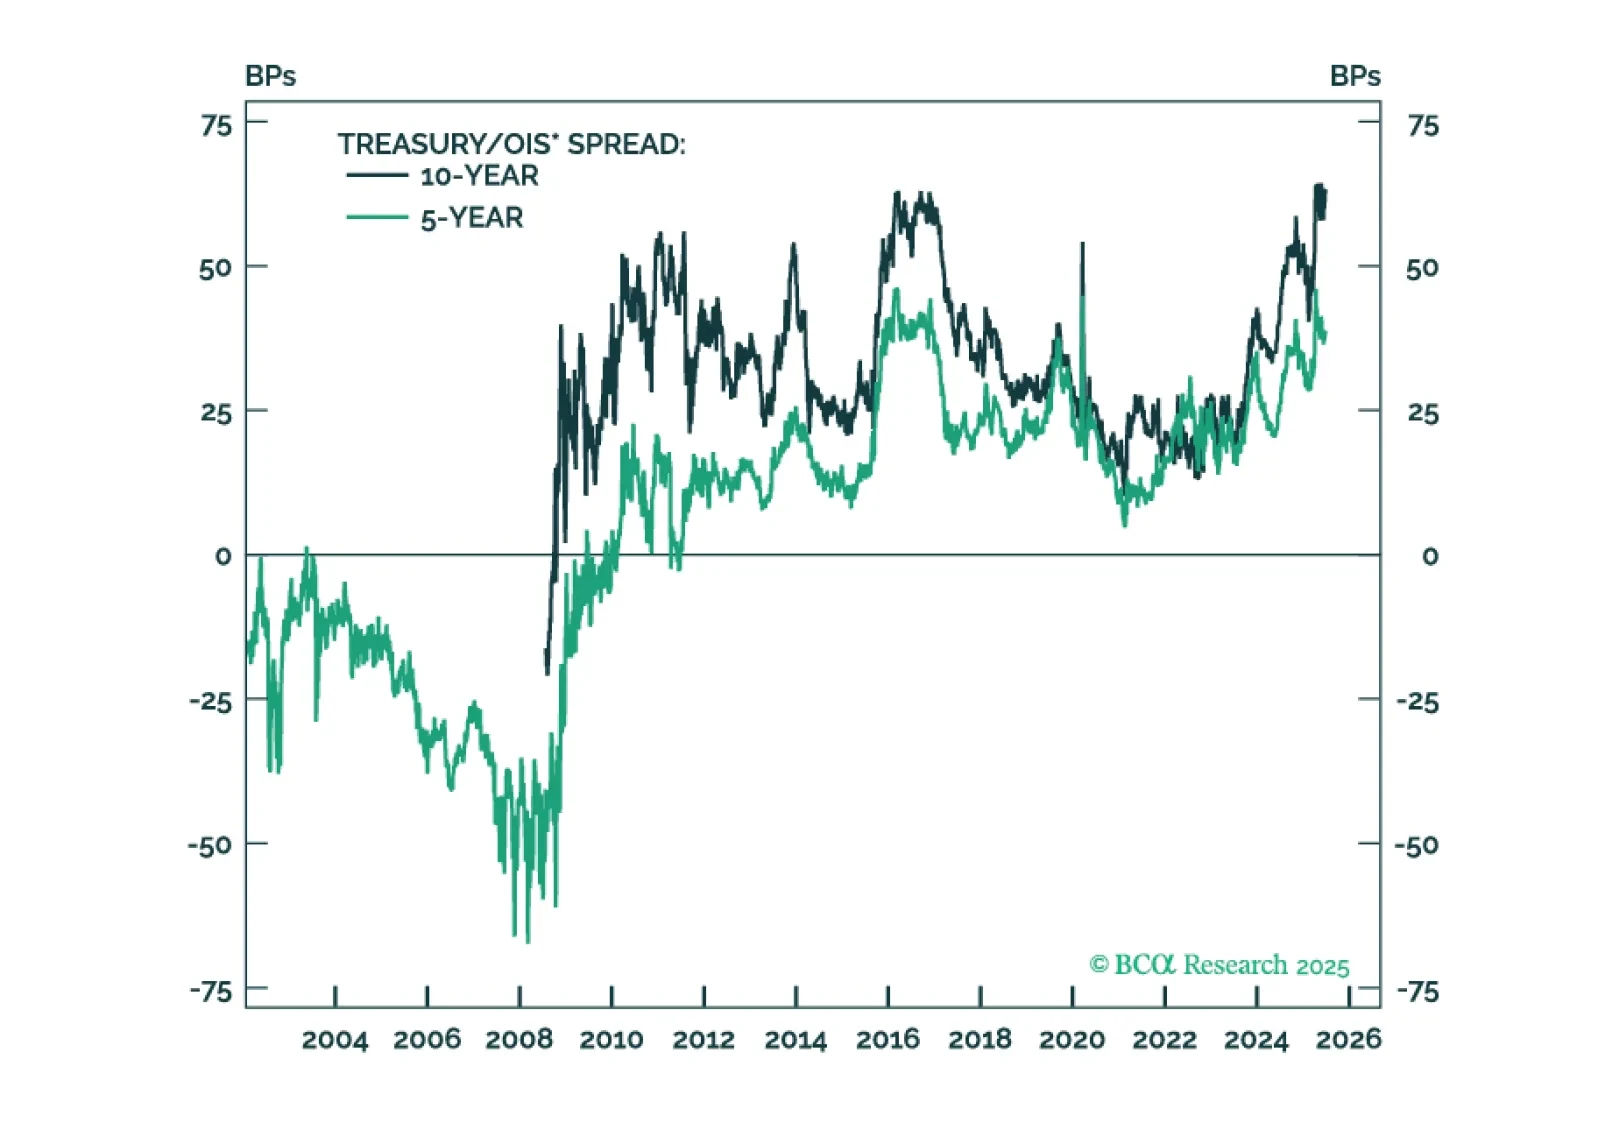
Special Report The Treasury/OIS spread has exerted notable upward pressure on Treasury yields during the past year, but the factors driving the spread are now turning more favorable.
Investors should modestly underweight equities in their portfolios and look to turn more aggressively defensive once the whites of the recession’s eyes are visible. We think that will happen within the next few months.
Bank Credit Analyst In Section I, Doug underscores that the full weight of tariffs has yet to be felt on the US and global economies, against the dangerous backdrop of a softening labor market. In Section II, Jonathan presents the bullish case for the US dollar over the coming year.
Special Report In Section II, Jonathan presents the bullish case for the US dollar over the coming year.
President Trump’s big beautiful bill will pass but faces near-term hurdles and will not tighten the government’s belt. It will combine with renewed tariff implementation to generate near-term risk for both the bond and stock market. The Iran crisis fizzled, saving Trump from a major oil shock that could have derailed his second term.
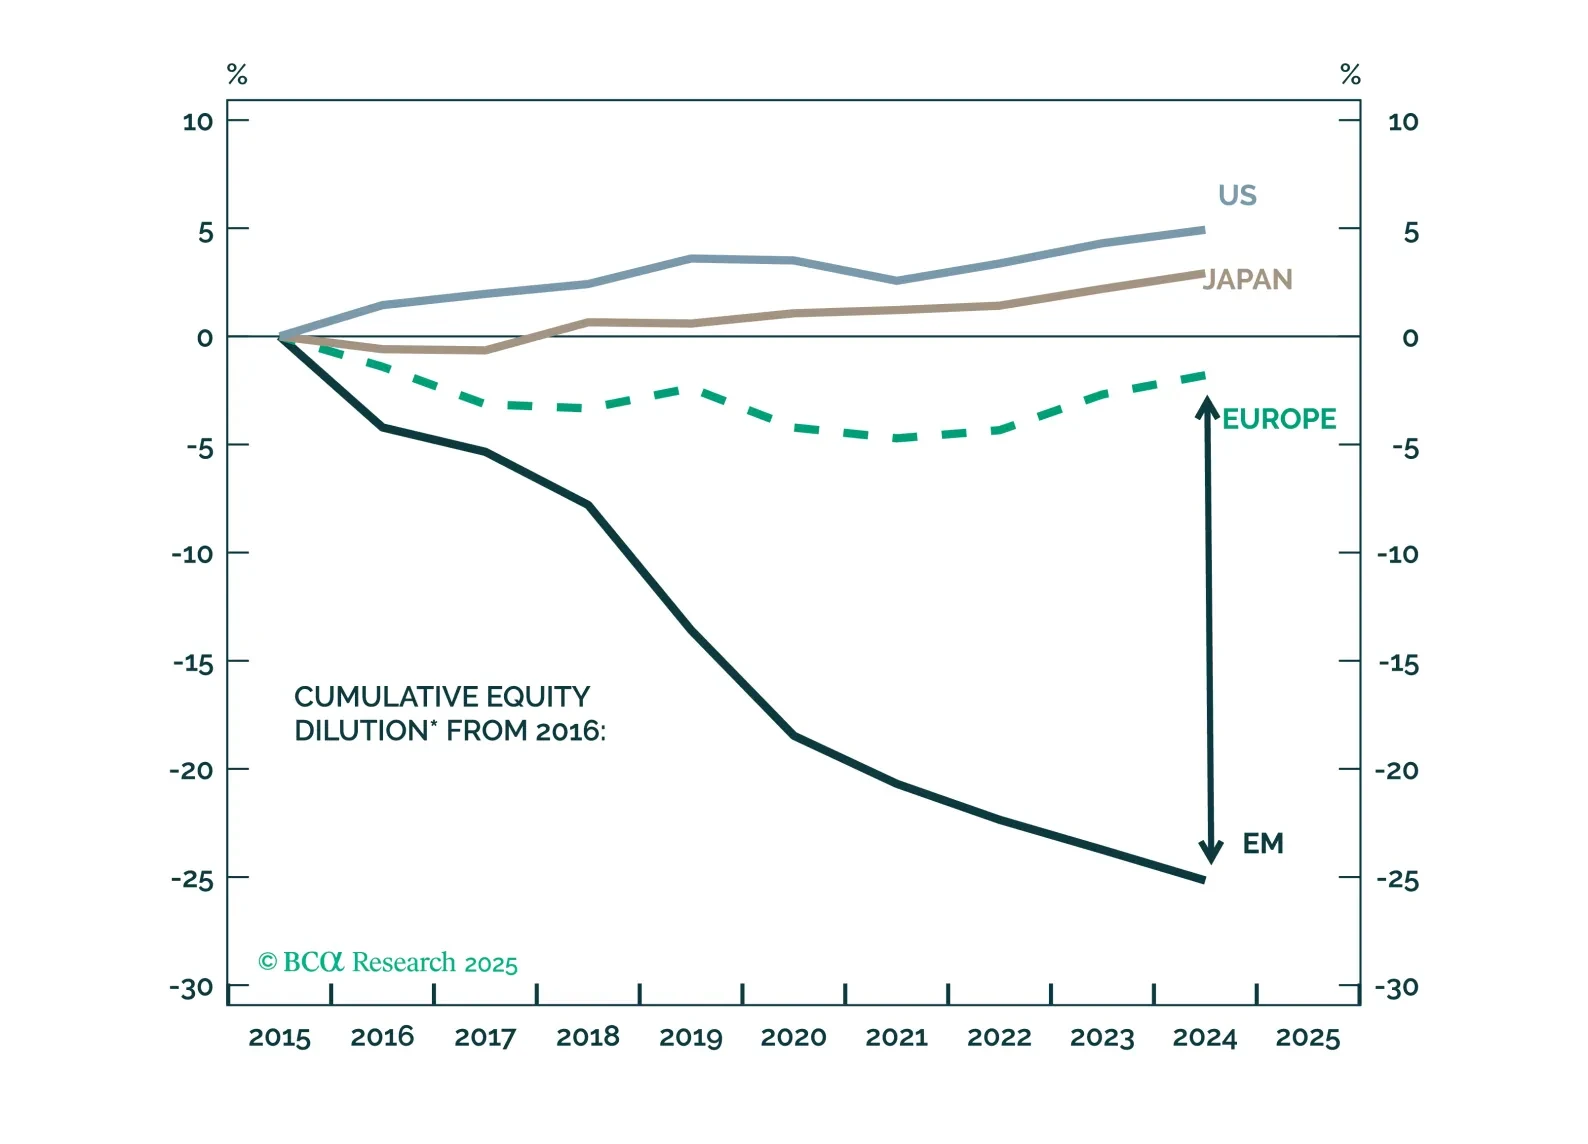
Special Report Dilution is one of the two main reasons why EM EPS has been much weaker than EM GDP and EM non-diluted profits. We calculate “pure” dilution – adjusted for companies’ inclusion and exclusion from the stock index – for various bourses around the world. To our knowledge, this is the first time this analysis has been conducted.