Latest from BCA Research
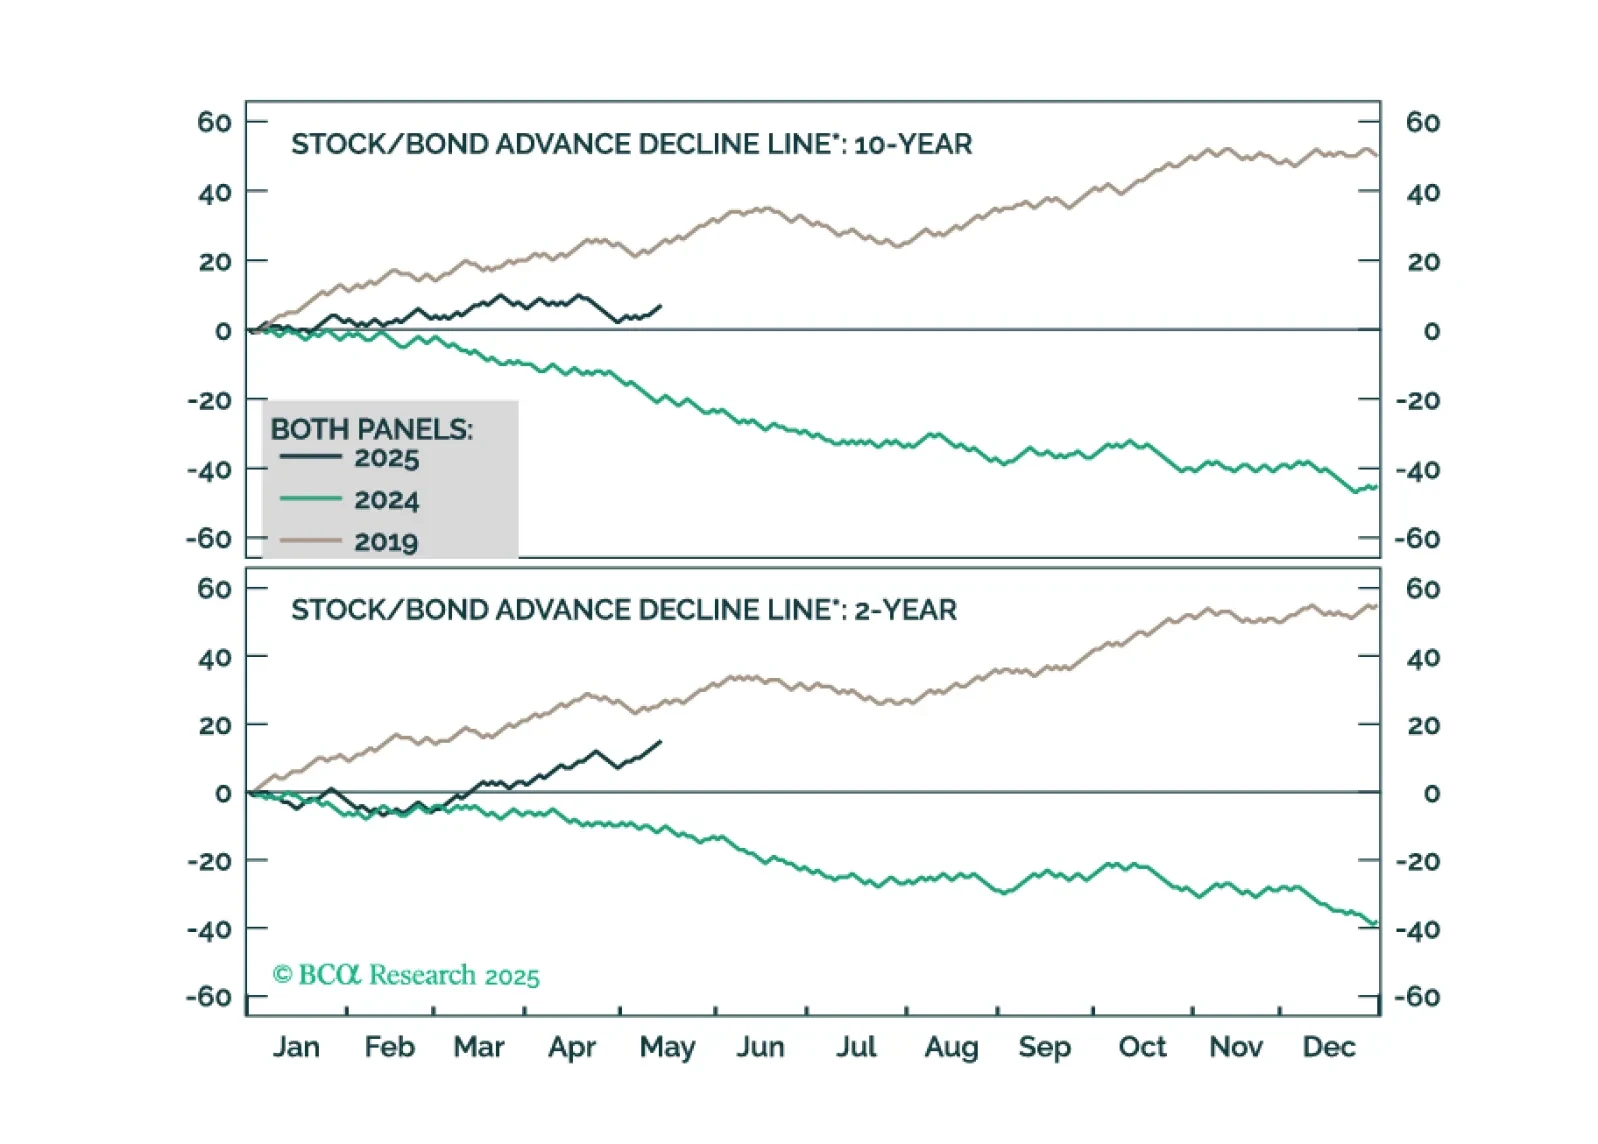
Tariff front-running behavior makes the April hard economic data difficult to interpret, but we take the strong reading from Food Services spending as a signal that the US consumer has not yet buckled.
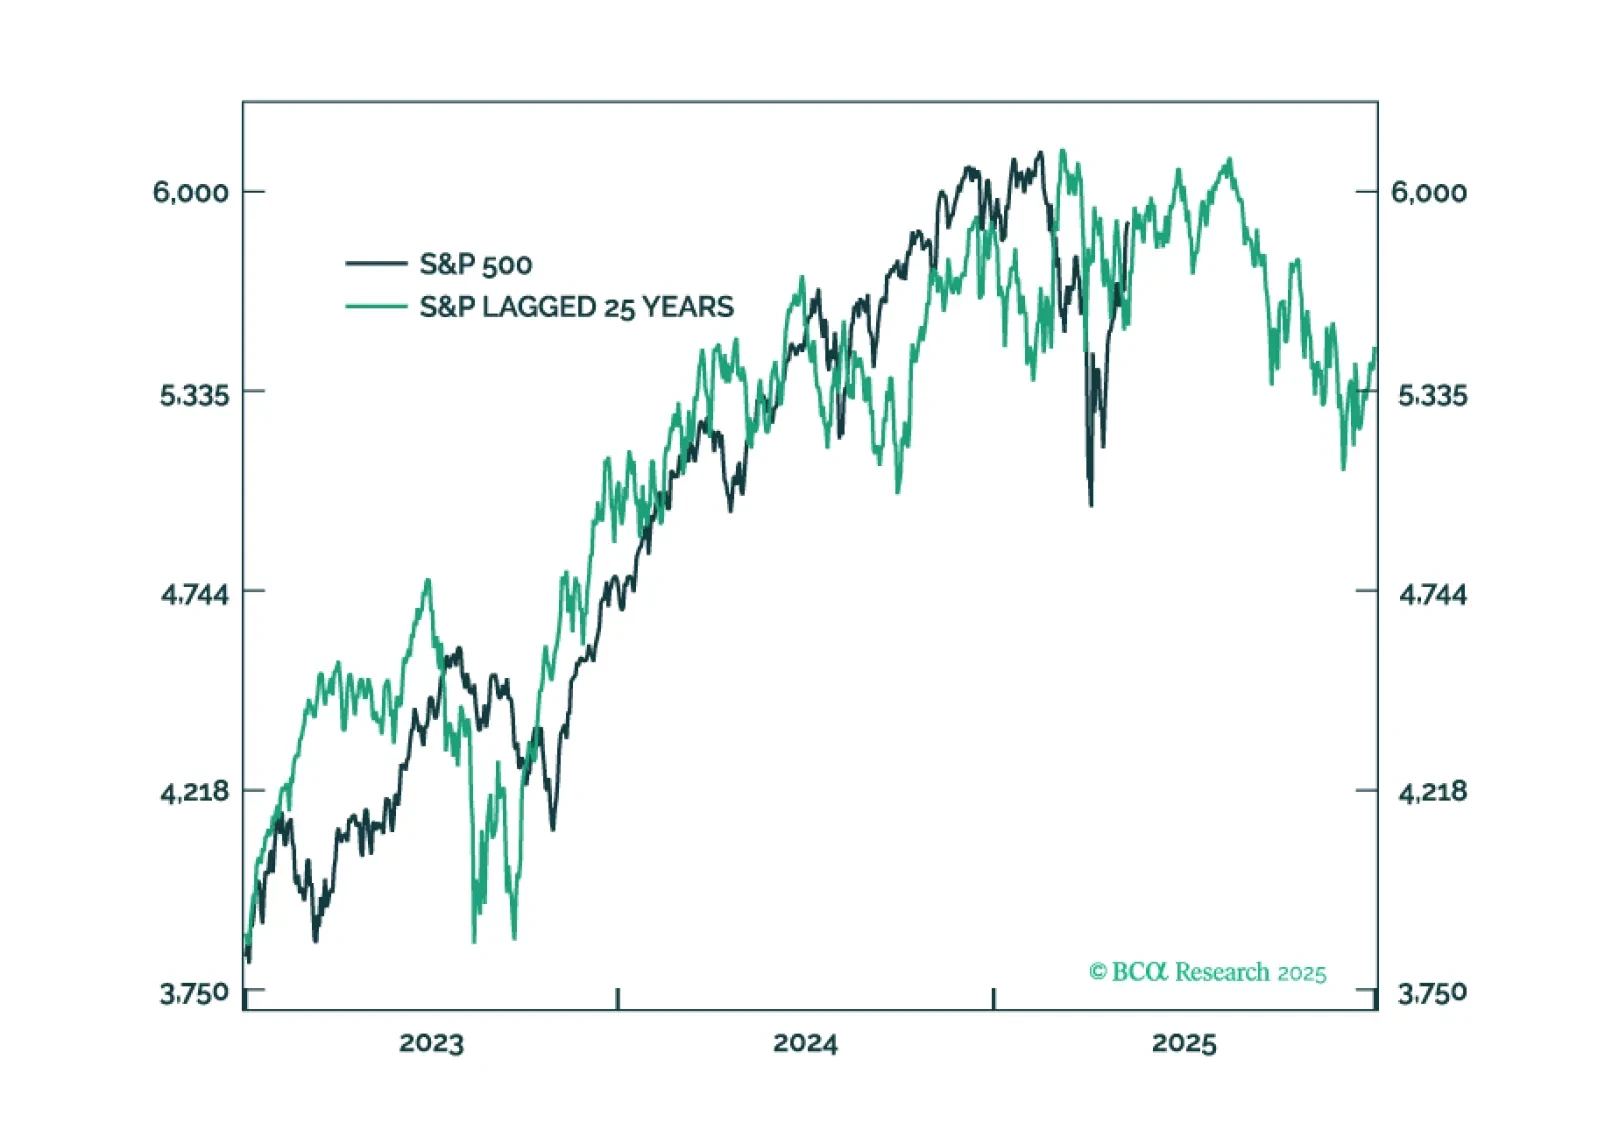
This year’s plunge in tech stocks followed by the recent strong countertrend rally is eerily reminiscent of 2000. But the market and economic parallels between 2025 and in 2000 run much deeper. This report lists 10 striking parallels between 2025 and 2020, then highlights some important differences, and ends by describing how the rest of 2025 might unfold based on a playbook that is: 2025 = ‘2000 with some tweaks.’
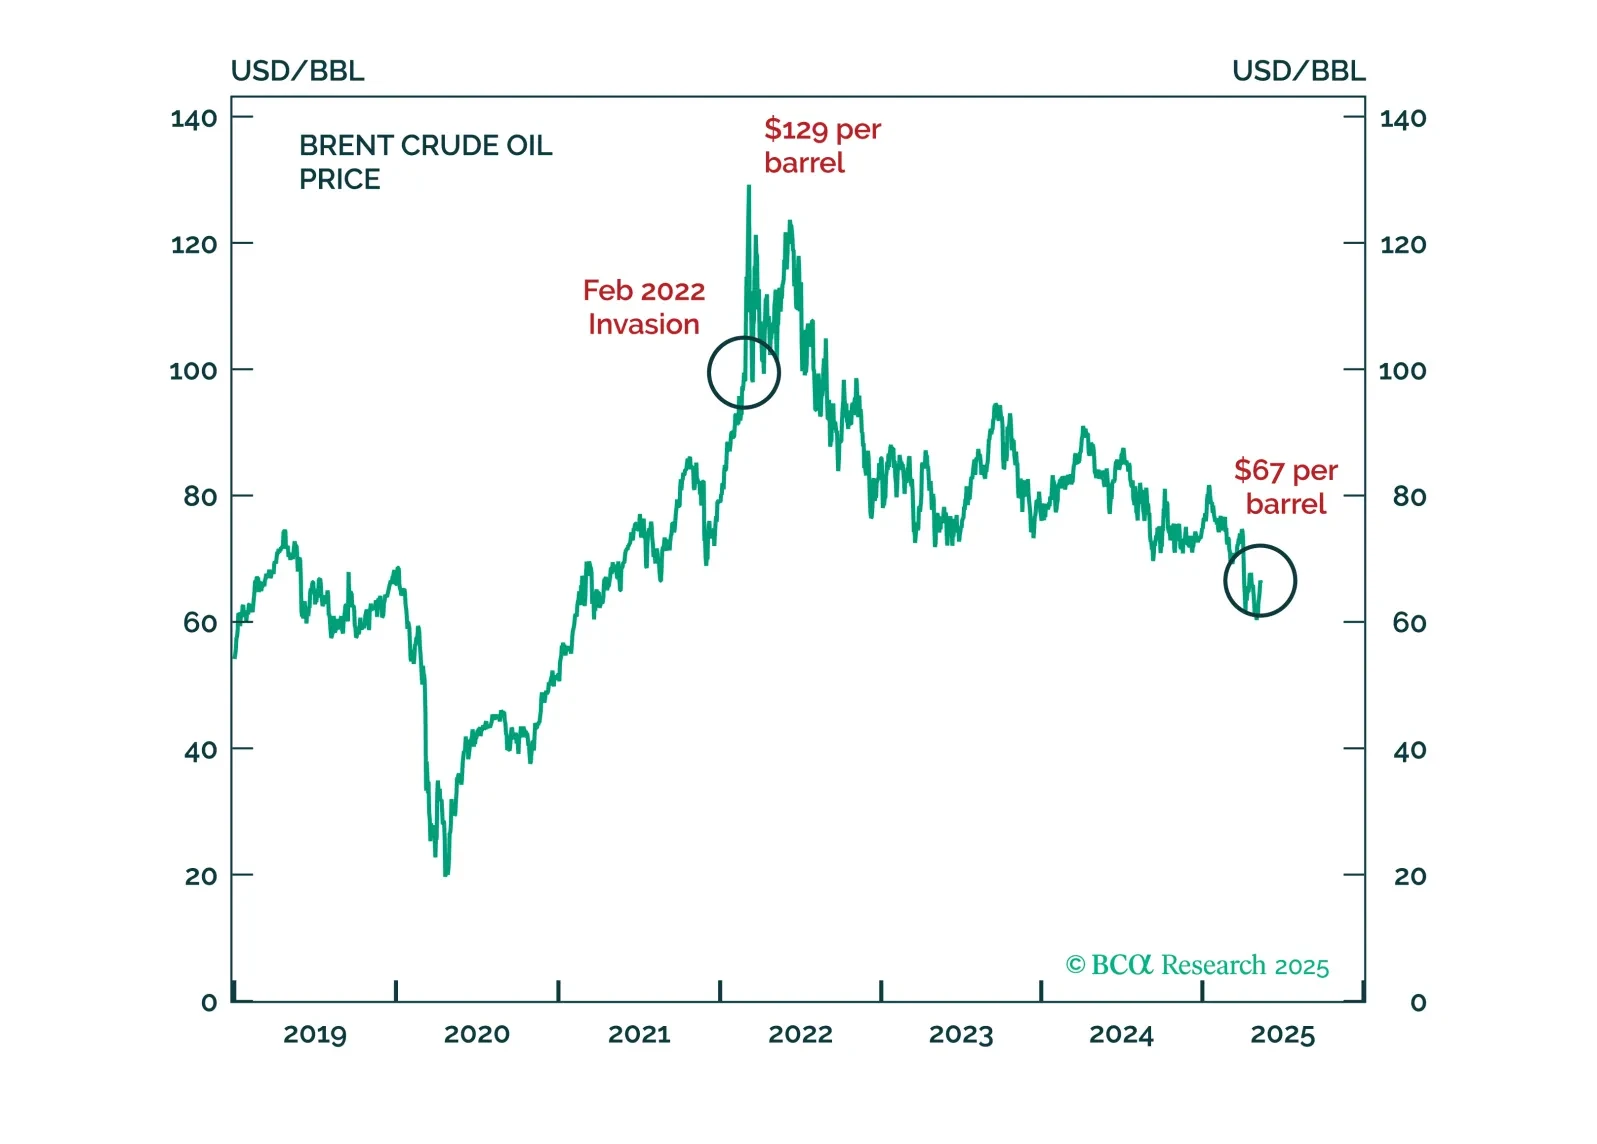

Although tariffs have receded, they are still high enough to weigh on growth, especially given that underlying economic momentum in the US was weakening going into 2025. The possibility of a fiscal crisis only adds to the risks.
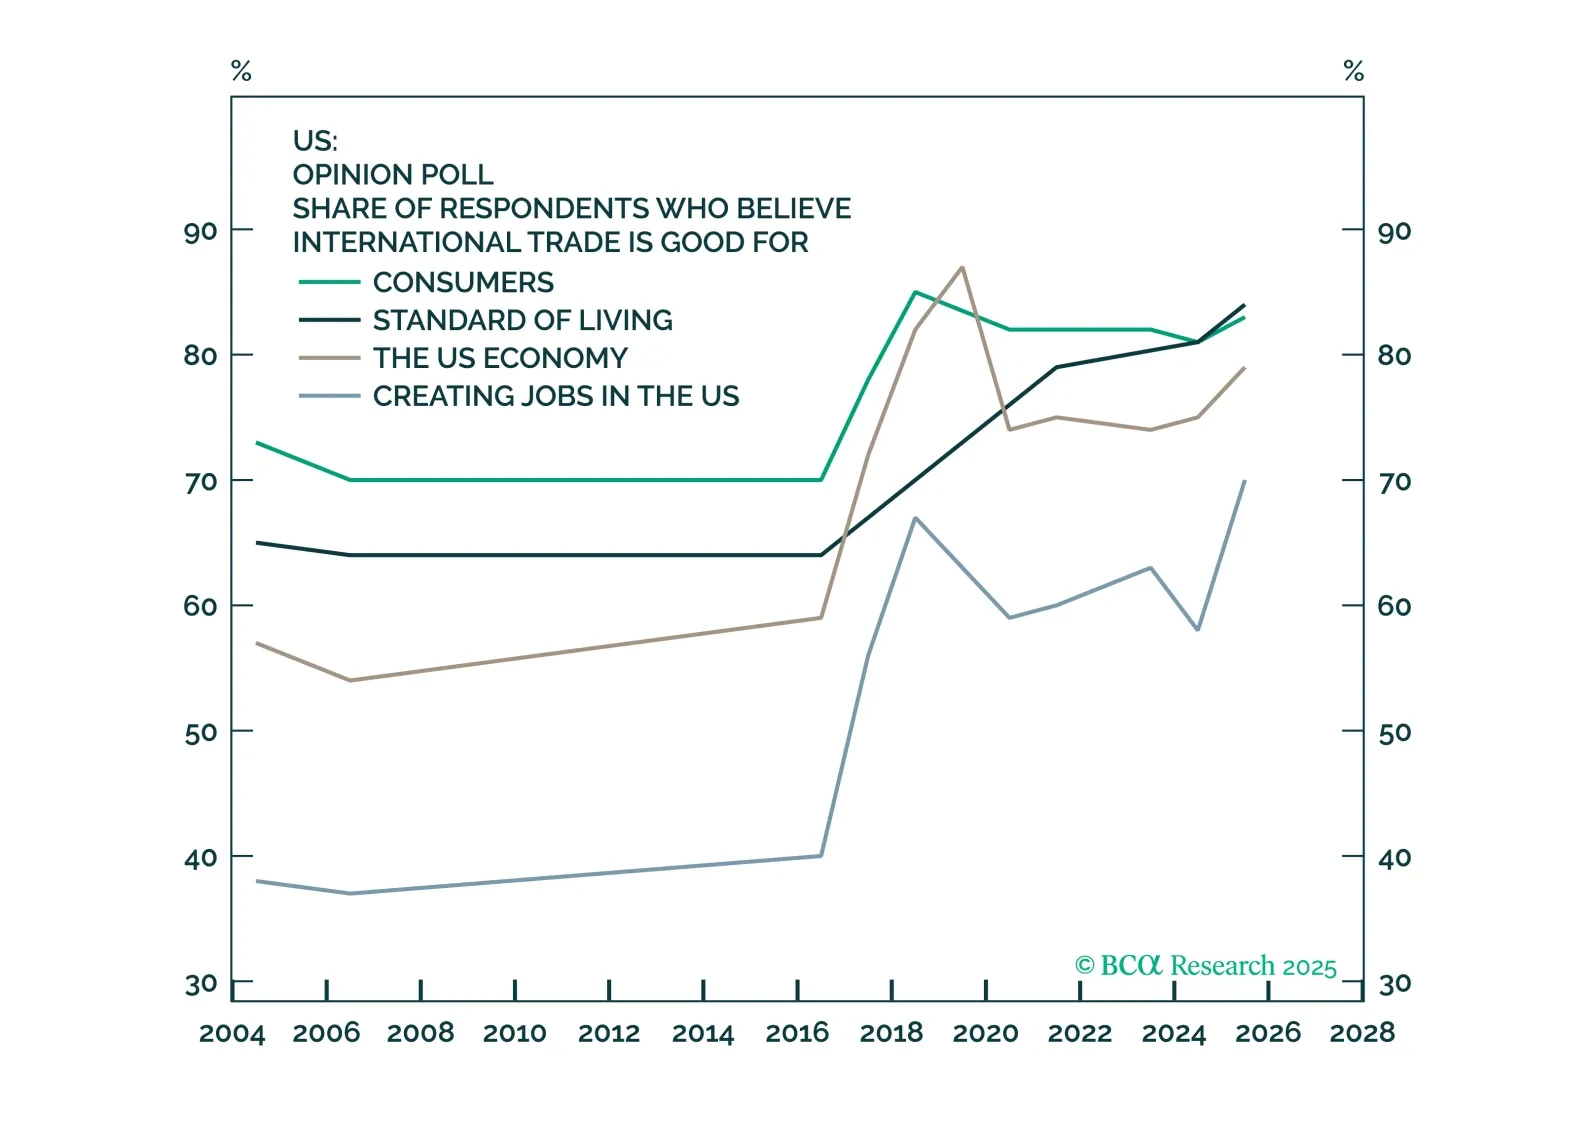
President Trump has pivoted towards negotiations as quickly as we expected (as in: QUICKLY). However, we did not expect the pivot on China to be as thorough and immediate. Markets have cheered the event. Not merely because US trade with China is substantive, but because investors are (correctly) assessing that if Trump can make a deal with China, he can make it with everyone. And he will. Nonetheless, investors should expect one or two more twists in the saga.

Markets are pricing out the worst trade policy fears, and while tariffs will still dent earnings, the impact looks smaller than initially feared. With sector rotation gaining traction and oversold names rebounding, we are adjusting our portfolio to reflect the rotation thesis.

A weakening economy will apply downward pressure to Treasury yields, but the Trump term premium will keep long-dated yields higher than they would otherwise be. This makes Treasury curve steepeners the most attractive trade in US fixed income.

Utilities remain a long-term structural investment theme thanks to the tailwinds from GenAI, EV, and onshoring. However, there is little upside left over the tactical investment horizon as all the positives are priced in. We close our overweight and book profits.
The announced US-China deal has taken everyone – even us, the authors of the implicitly bullish Seven Steps of Maximum Pressure – by surprise. President Trump has signaled a pause in the fight against China. Yes, the situation can reverse, but when your Secretary Treasury says things like “neither side wants to decouple,” the world should listen.

The easing bias remains, but not all central banks are equal. This Central Bank Monitor update reveals who is ready to cut more and who is still pretending not to.