Latest from BCA Research

Going into this year, I was by far the most bearish strategist in the Bloomberg survey. A number of clients have reached out to me asking if I plan to change my end-year price of 4450 for the S&P 500 in light of recent events. The answer is “no,” since recent events have unfolded broadly in line with my expectations.
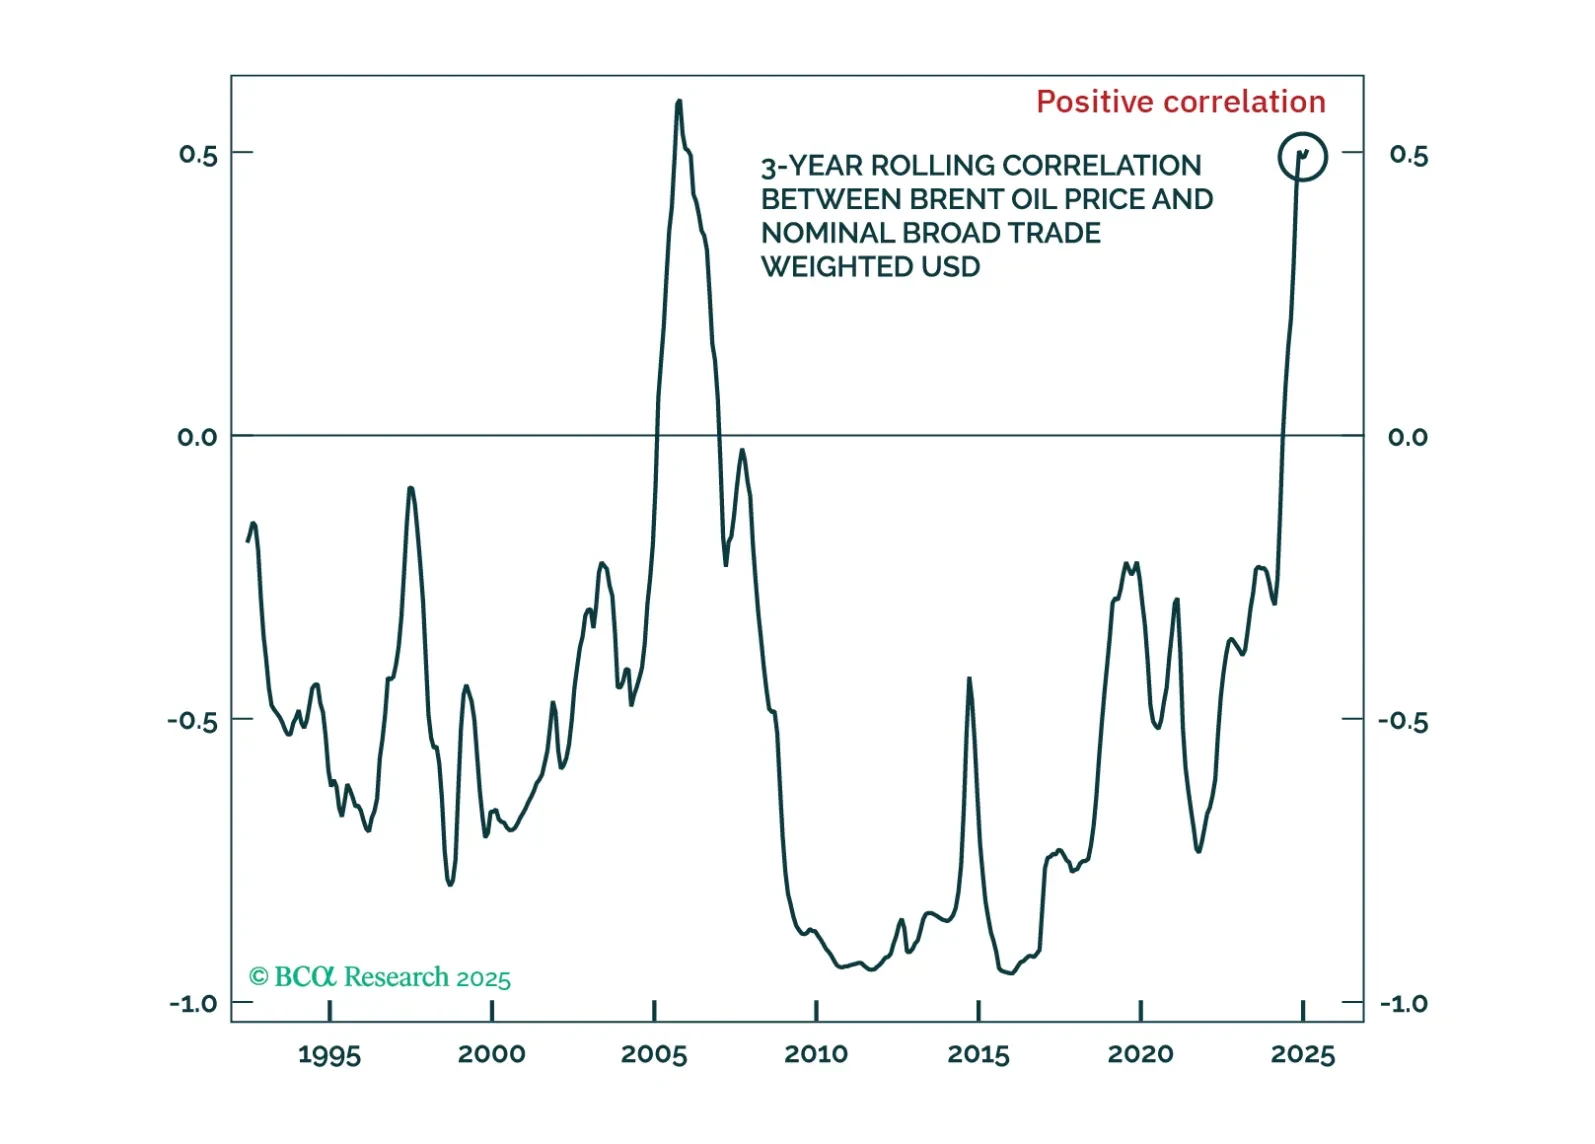
Commodity prices are succumbing to the risk-off environment triggered by President Trump’s reciprocal tariff announcement. The latest events and market moves raise several important questions about the outlook for commodity markets. In this Strategy Report we address some of the most pressing questions raised during our recent discussions.

The stimulus measures driving the post-COVID expansion were beginning to wane after five years and pointing the economy in the direction of an organically occurring recession. Now that DOGE and the multi-front trade war have sped up the timetable, we reiterate our risk-off recommendations.

Trump’s tariff shock will push Europe into recession — but it’s also triggering a powerful integration response. In this report, we lay out the tactical case for staying defensive and the structural case for going long European assets when the dust settles.
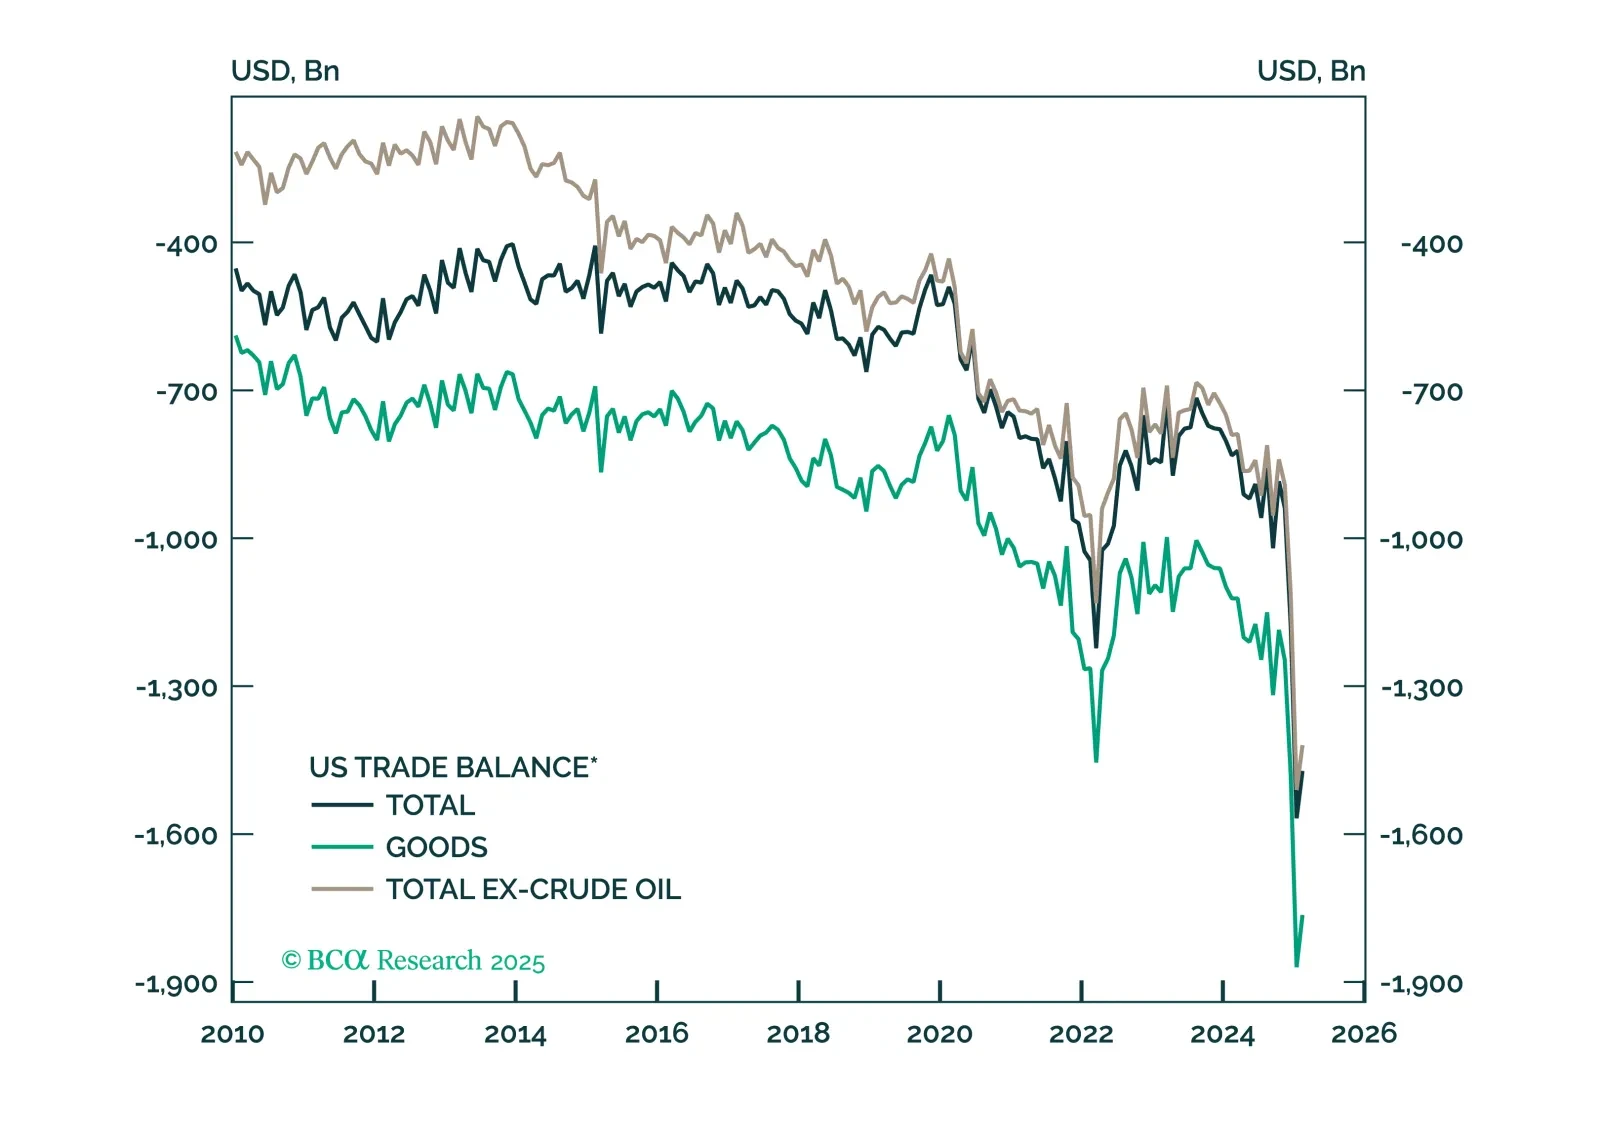
This report looks at the FX implications of the Trump tariffs, and the review of our Q1 trades.
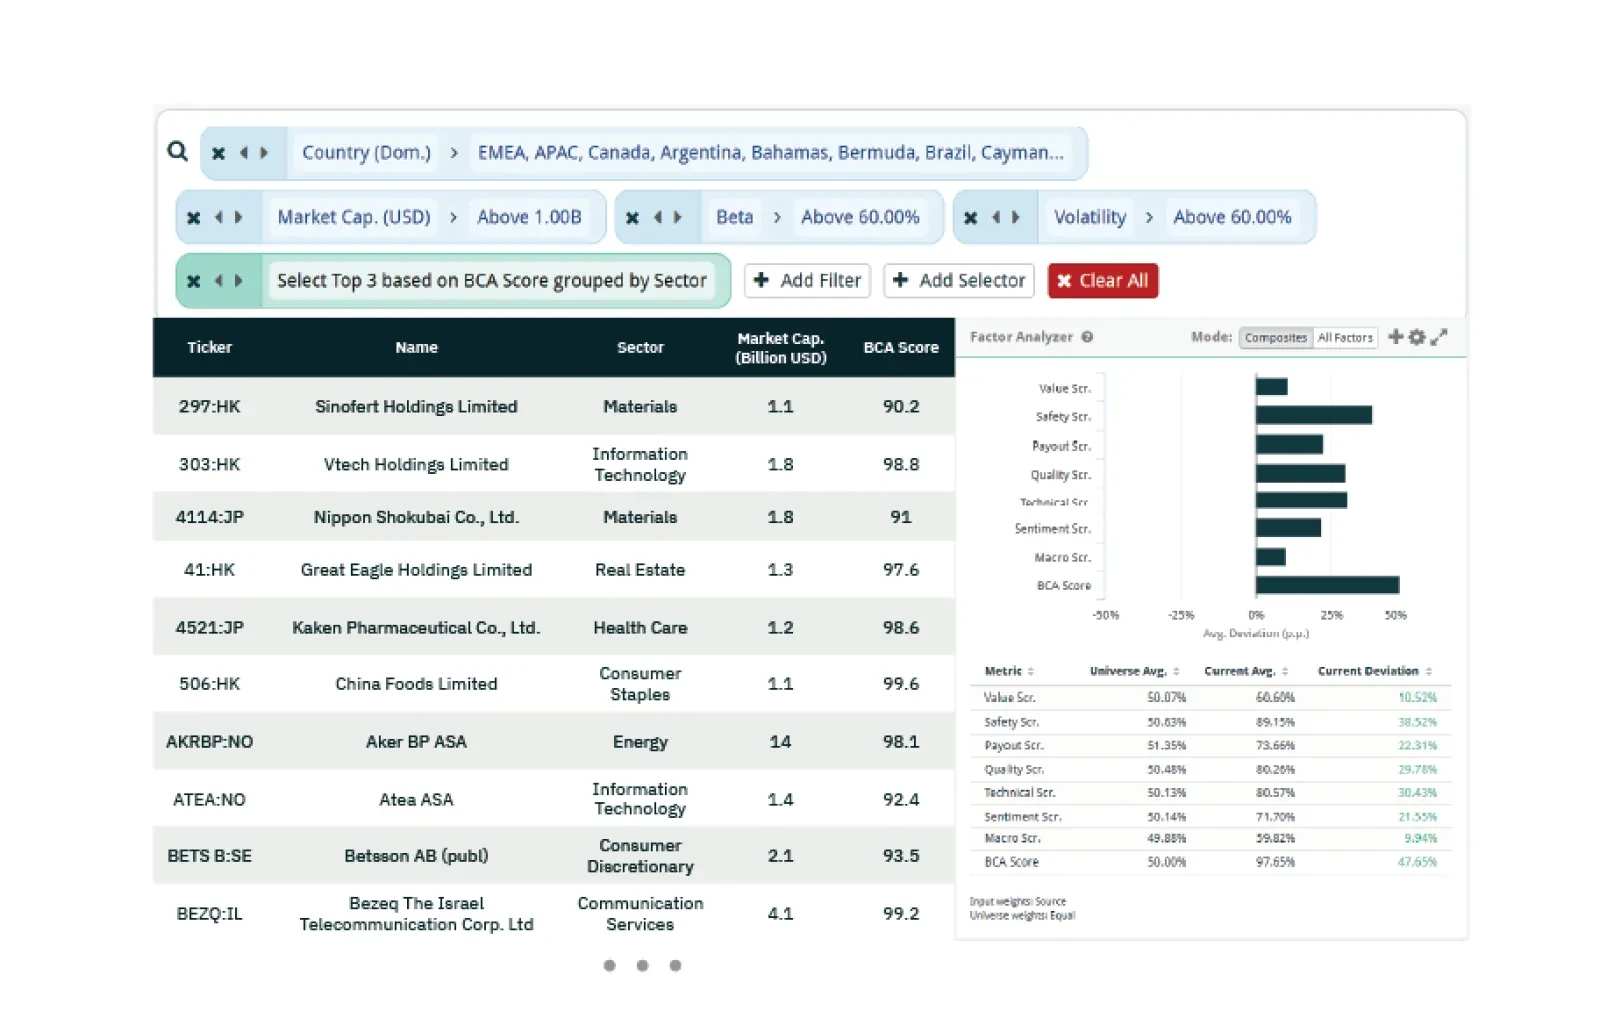
This week, our three screeners cover: Equity plays in Low Vol & Low Beta outside the US; Chinese stocks; and stocks that are buys according to the PEG ratio.

The March employment report showed strong job growth, but the labor market remains in a fragile state and the demand shock from tariffs could be the catalyst that tips it over the edge into recession.
Did you know that the high-quality Japanese zippers you use every day are macro relevant? That is because YKK dared to sue – and win – against President Richard Nixon 10% across-the-board tariffs.
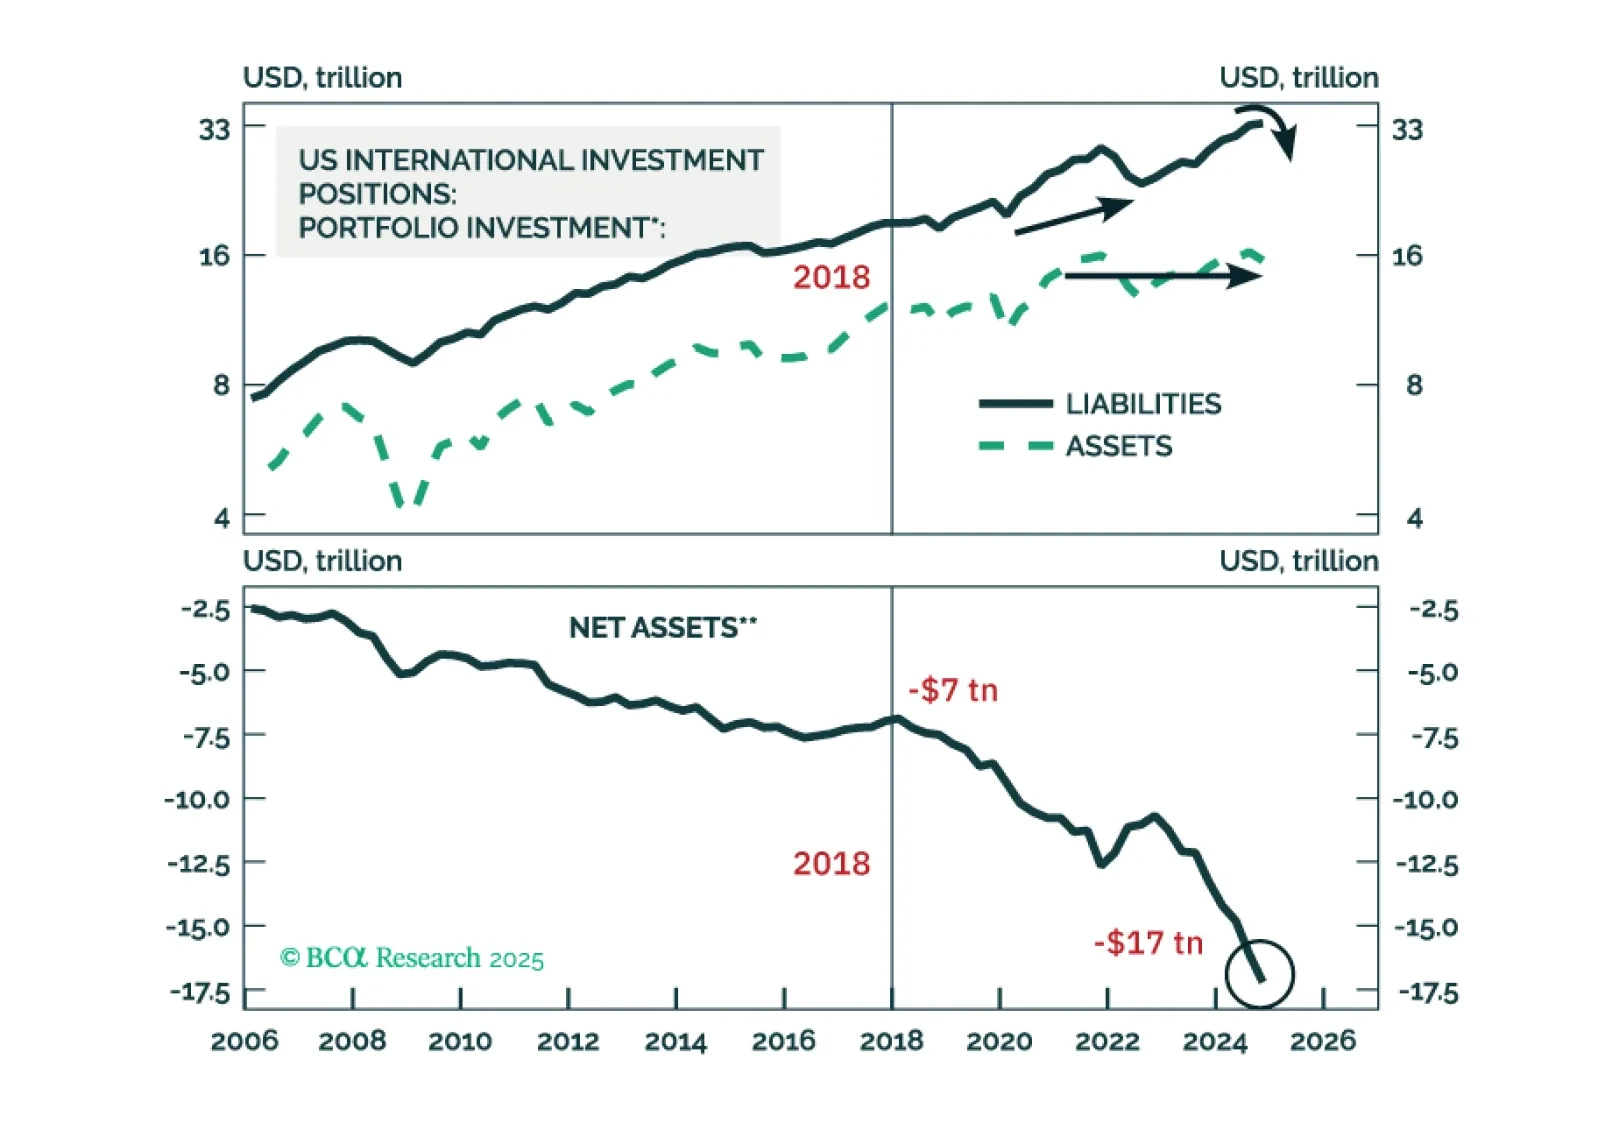
On the one hand, US tariffs are much more deflationary for the rest of the world than for the US, so interest rate differentials might move in favor of the US dollar in the near term. On the other hand, portfolio outflows from the US will weigh on the greenback over a cyclical horizon. We recommend buying Mexican and Central European domestic bonds.
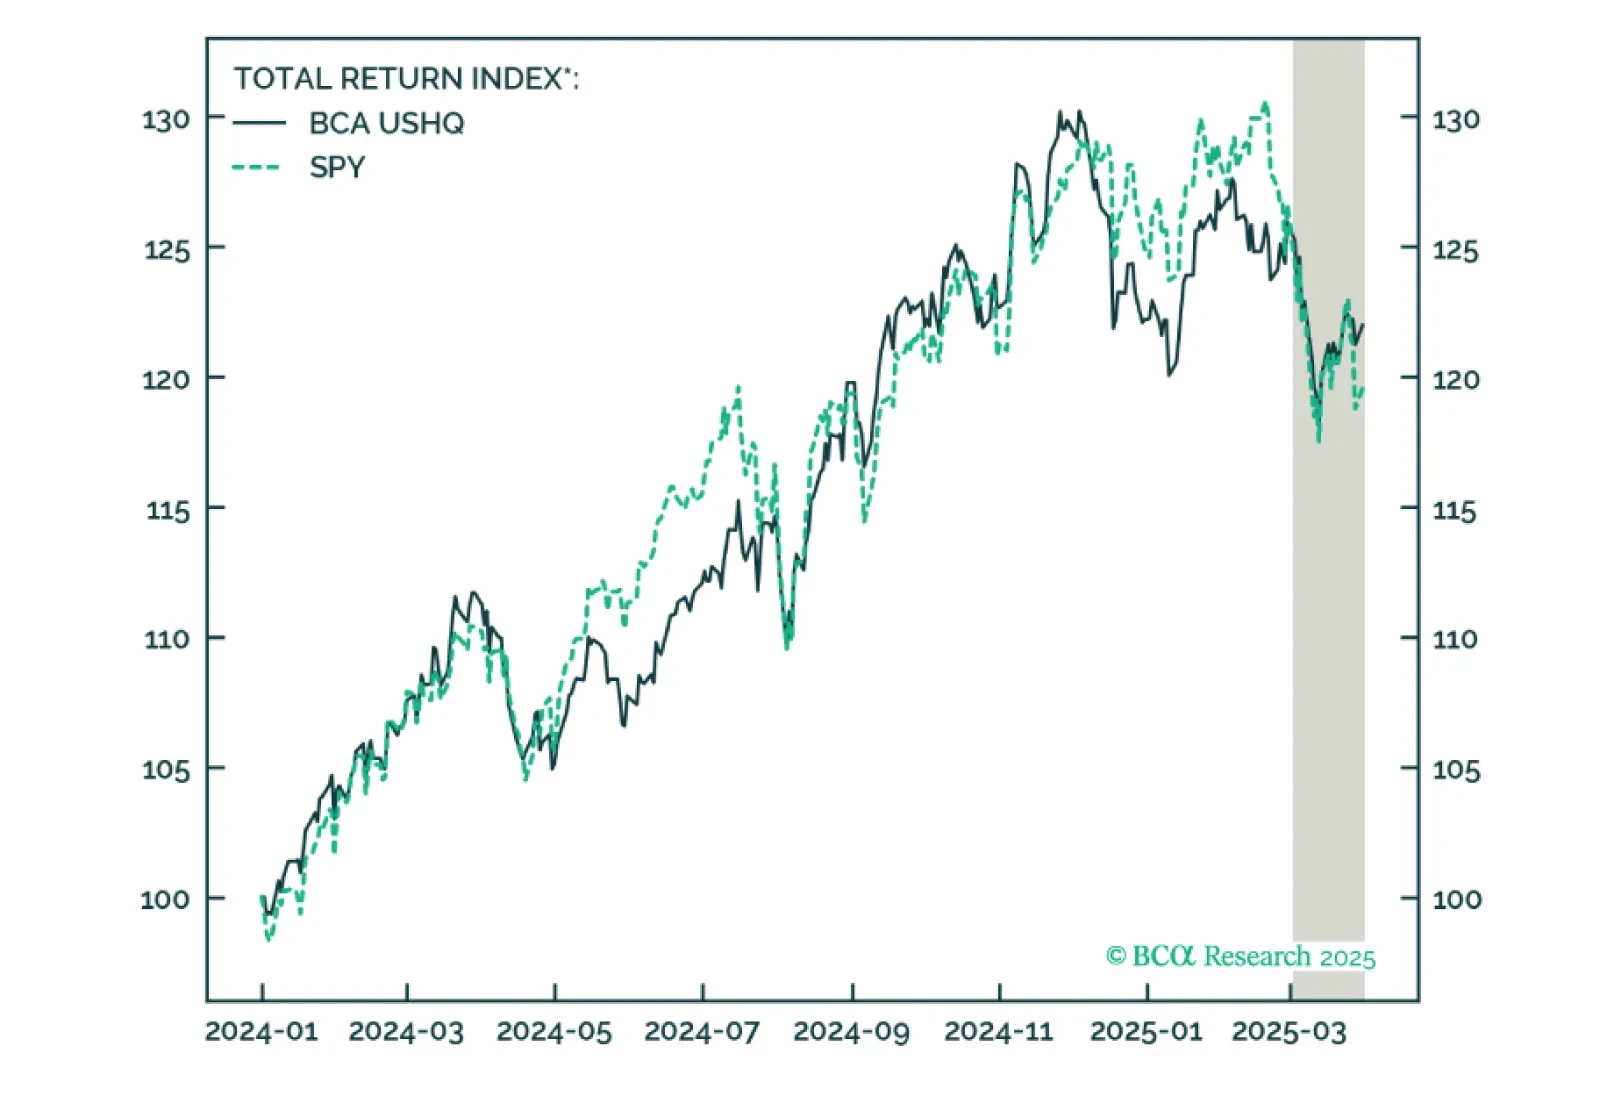
The US High Quality (USHQ) portfolio outperformed its benchmark in March, despite realizing a negative return. USHQ returned -2.6%, whilst its SPY benchmark returned -3.9%. Over a trailing-quarter basis, USHQ posted meaningful outperformance vs. benchmark, generating +230bps of excess return, while also exhibiting lower volatility and a smaller drawdown.