Latest from BCA Research
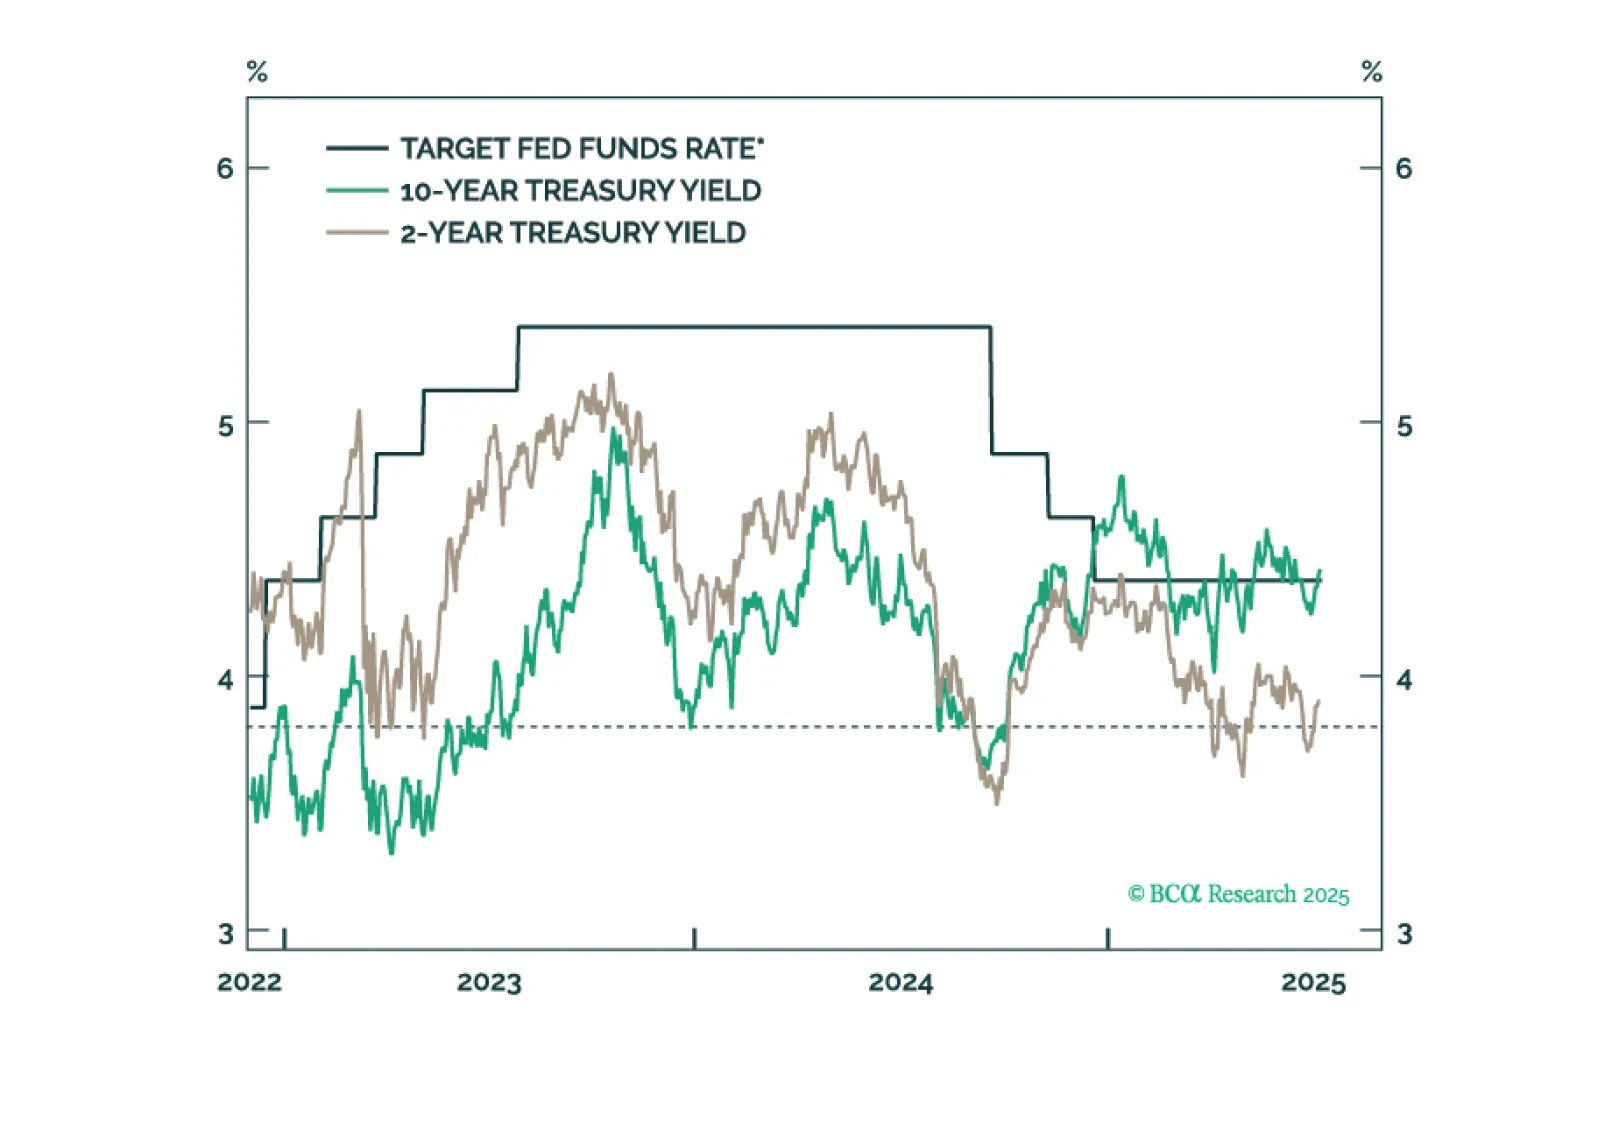
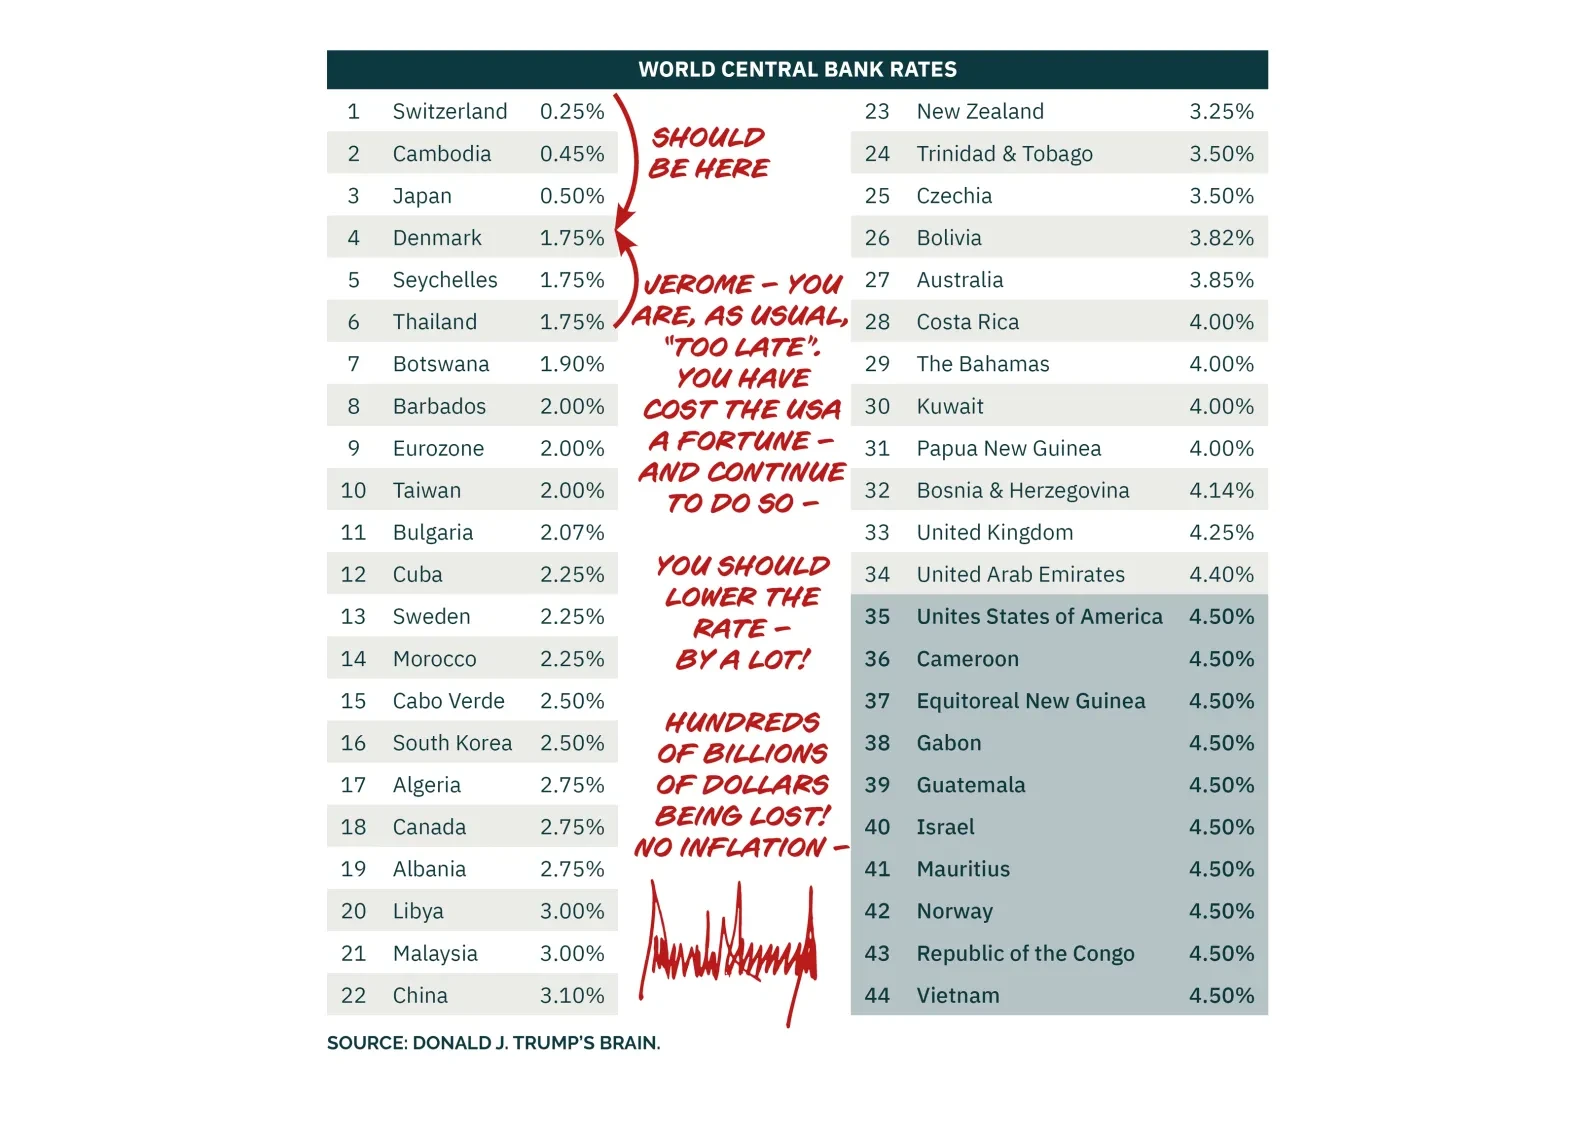
We have thrown caution to the wind and gone overweight equities. Why? Three reasons: the Fed is under immense political pressure to pivot, USD has depreciated, and inflation is in check. It is going to be a very difficult job for Fed Chair Powell to ignore the downside risks to both inflation and growth. If he does, he will be accused – correctly – of political bias.
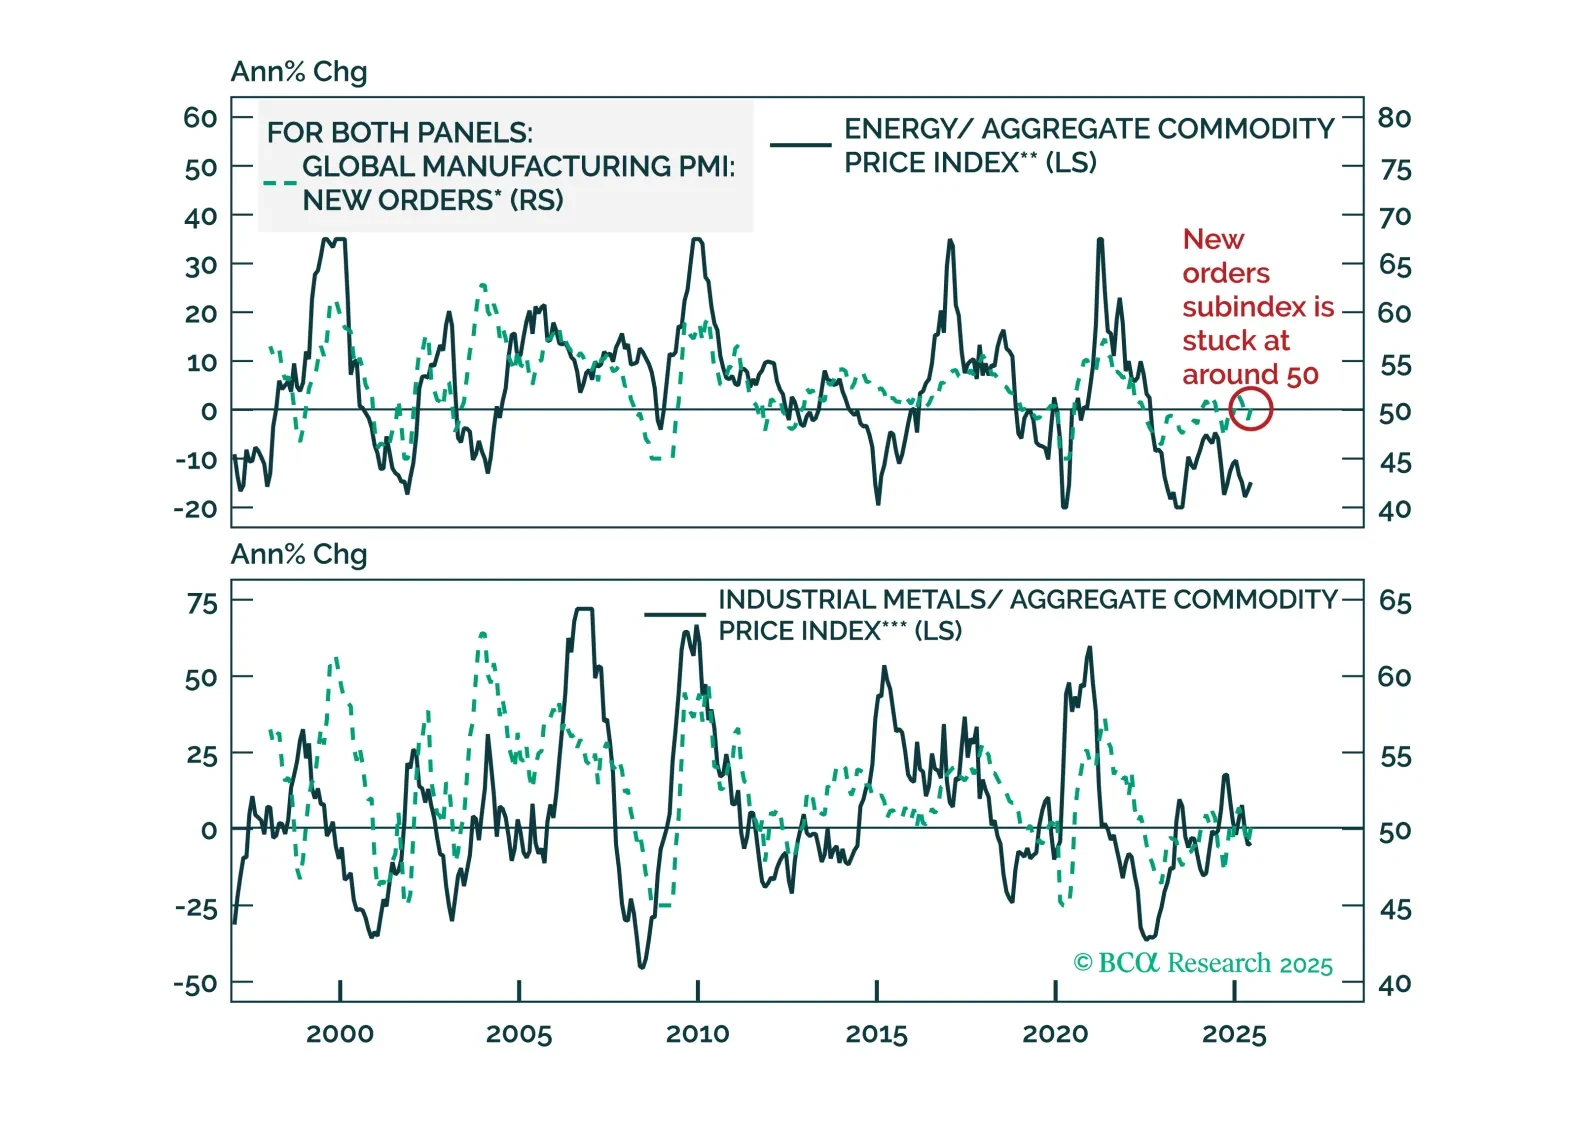
An update on the key themes and views that will shape commodity markets through the remainder of 2025.

Markets are pricing a return to a neutral policy stance for the major central banks within the next 12 months. However, recession risks still loom amid slowing growth. We unpack where recession risks are underappreciated and what it means for bond positioning.

This week our three screeners identify stocks that are likely to keep delivering deliver earnings surprises in the US, European small caps that are high quality and mean reverting, and Japanese large caps picks across GICS 1 sectors.

We upgrade European small caps to maximum overweight and double down on our existing recommendation to go long European small caps relative to US ones.

Earnings growth should continue to support equity performance this year. However, after blockbuster gains, some profit-taking is likely. We recommend booking profits and increasing exposure to Defensives.

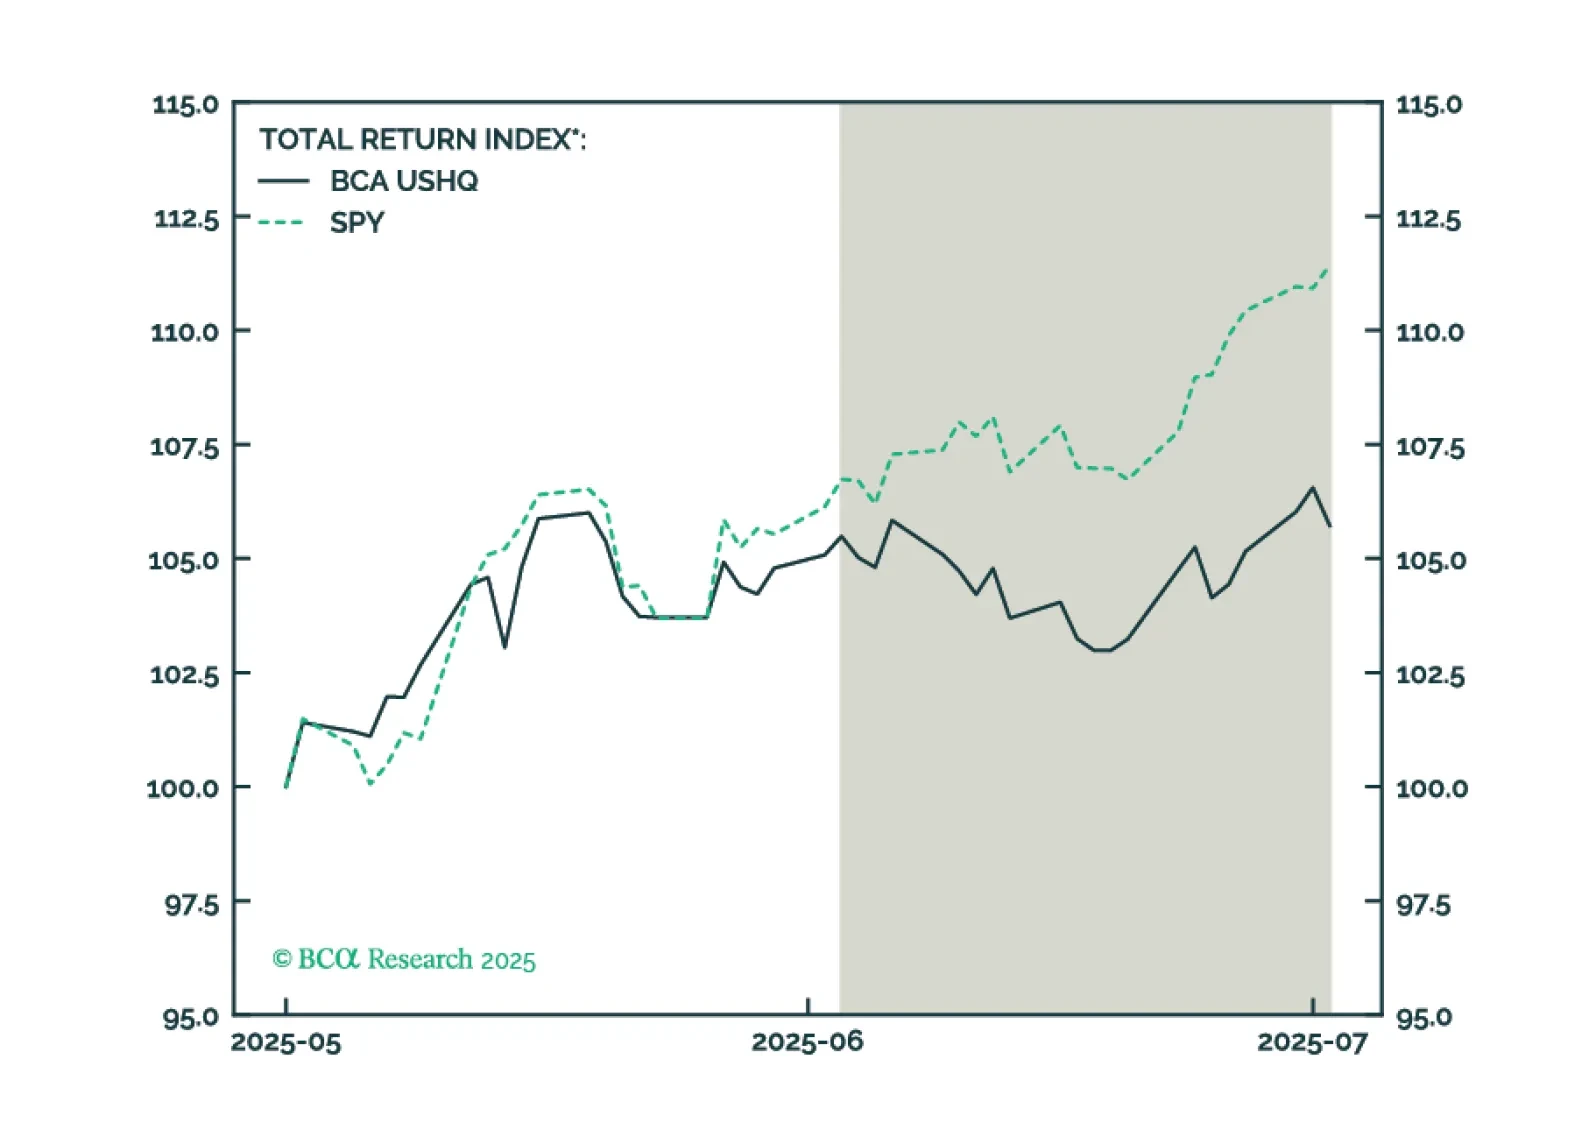
The US High Quality (USHQ) portfolio underperformed its benchmark through June, returning 1.2%, whilst its SPY benchmark returned 5.1%. On a trailing three-month basis, performance was notably weak vs. benchmark, with USHQ underperforming by approx. 600bps.
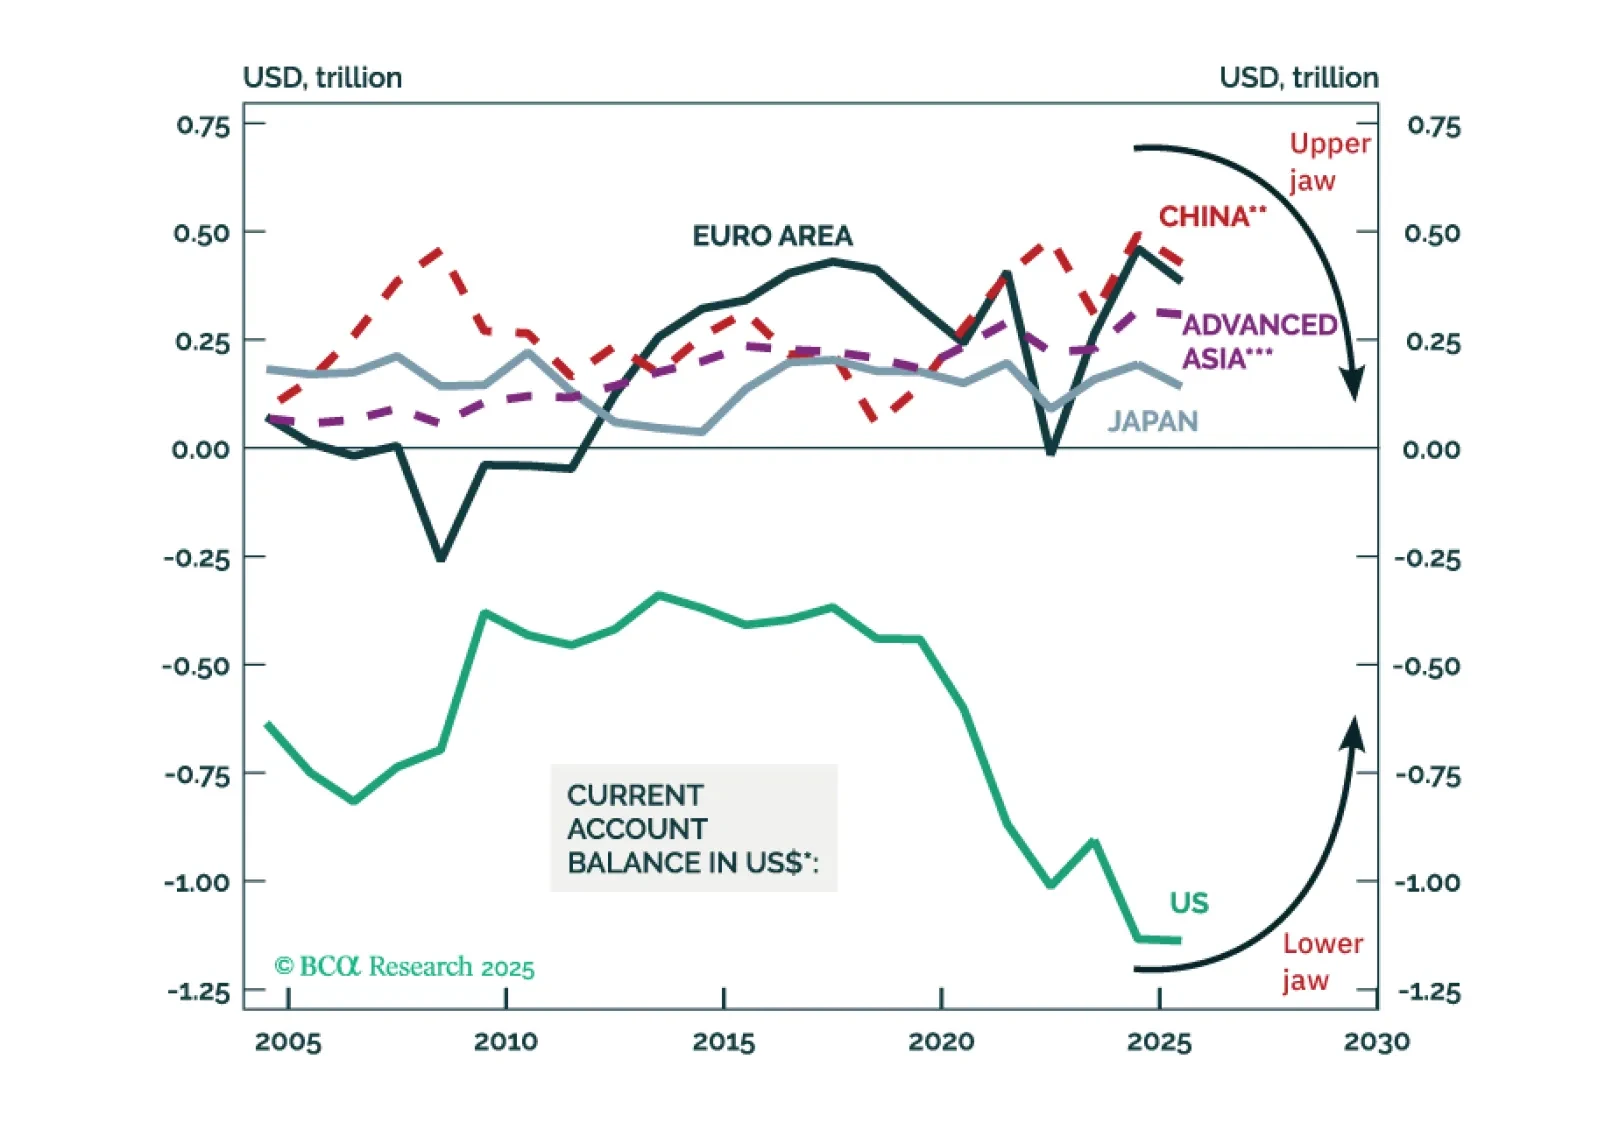
Alligator Bite #1: As US net portfolio inflows decline (the alligator's upper jaw closes), its current account deficit must narrow (the lower jaw will also shut). Alligator Bite #2: As the US current account deficit shrinks (the lower jaw closes), current account surpluses in the rest of the world will narrow (the upper jaw will come down).