France


The bond vigilantes are circling over several targets right now: France, the UK, and Japan. But France is the most vulnerable because of a toxic combination: a total debt ratio well above 300 percent plus the worst primary deficit in the G7 plus political gridlock, which will get even worse if Prime Minister Francois Bayrou loses the September 8th vote of confidence in his minority government. We explain why the ECB cannot save France, and the investment implications. Plus, we unveil our brand-new complexity ‘heat map’ for global asset allocation which leads to a new tactical trade to underweight world communication services (WTEL).

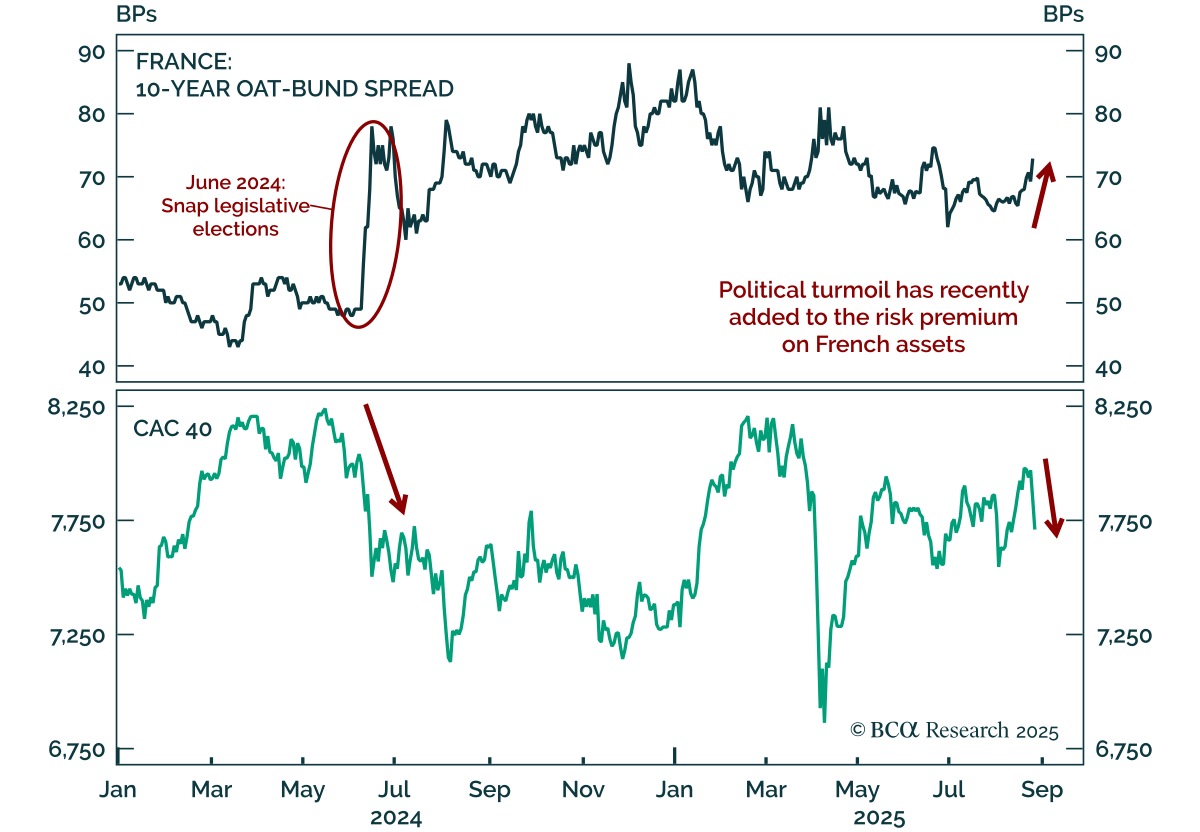
Political instability will persist in France as PM François Bayrou loses the confidence vote. The nomination of a new PM will not end the country’s political paralysis and will further fuel fiscal fears. Investors should remain underweight French OAT. French equities, especially French banks, should be bought on dips.

This week our three screeners explore: UK stocks that are cheap and offer a geopolitical hedge; French stocks that are sensitive to China; and US Value and dividend paying stocks.


France’s political turmoil is far from over, and fiscal fears are growing. This is not a bond-friendly environment. In contrast, it is a good time to upgrade French equities. As the 2027 presidential race is about to begin in earnest, we make an early call on its outcome.

Europe’s deflation problem is getting harder to ignore. This week’s ECB cut is just the beginning — tariffs, the euro’s rally, and softening demand all point to more easing ahead. We explain what it means for yields, equities, and EUR/USD.

We are at a pivotal moment for Europe, supported by structural reforms and macro catalysts. While expanding credit markets and lower rates favor Private Equity over Private Credit, opportunities vary by segment. Large+ Buyouts are attractive as markets have priced in structural challenges. We downgrade Europe Private Credit, remain neutral on Europe Private Equity broadly but overweight Europe vs. North America in PE portfolios.

Questions about fiscal risks and their impact on bond markets have become more frequent in client conversations. This Special Report provides a framework to assess a country’s fiscal sustainability and how it affects its bond market outlook. On an individual country basis, Spain has shown a remarkable turnaround in its fiscal sustainability outlook while the fiscal outlook for France continues to deteriorate.